
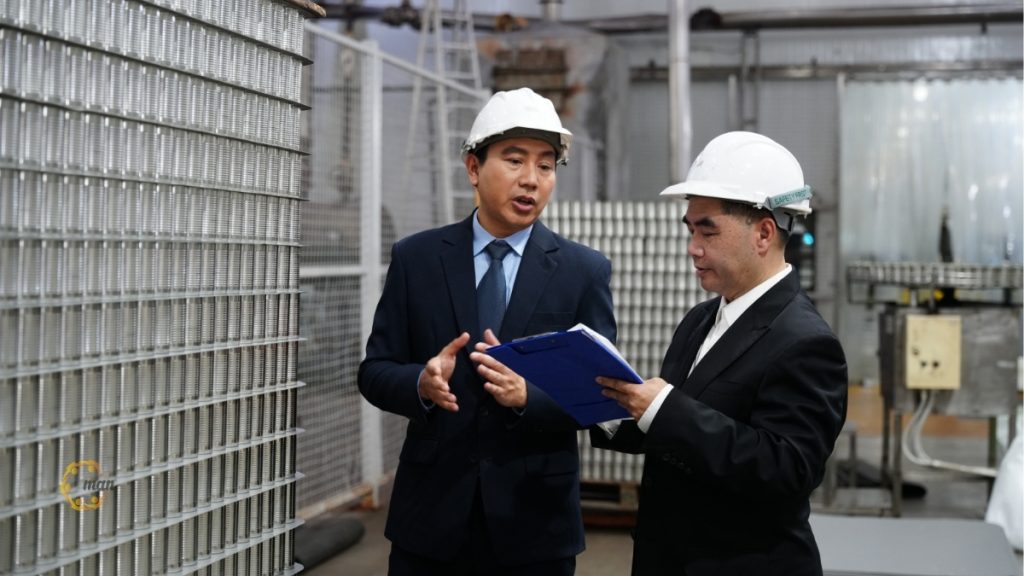
In a highly competitive market economy, managing cash flow and costs is no longer solely the responsibility of the finance department, but a matter of survival for the entire enterprise. This is especially true for manufacturing companies, where the process from raw materials to final products is incredibly complex. Therefore, tight control over accounting practices within a manufacturing business plays a core role in optimizing costs.
The seamless connection between departments, from warehouse and production to sales, requires a robust financial data management system. This article will provide the most up-to-date overview for 2026 of operational processes and insights that business managers can gain to make accurate business decisions.
Why is it necessary to divide accounting functions in a manufacturing business?
Completely different from purely commercial accounting, accounting in manufacturing businesses bears the crucial responsibility of determining product costs. The division of accounting functions within a manufacturing business helps create key control points:
- Industry specifics: Manufacturing businesses face challenges such as calculating work-in-progress costs, managing material consumption norms, and depreciating assets used in production. A small error in inventory management can distort the entire product cost.
- Strengthening internal controls: Clearly defined responsibilities help minimize the risk of fraud, asset loss, and accounting errors.
- Trends in 2026: Technology is changing the way we perform accounting tasks in manufacturing businesses. The integration of AI and next-generation ERP platforms automates data collection, allowing accountants to focus on analysis and forecasting instead of manual data entry.
See details: The entire accounting process for a manufacturing business.
Detailed analysis of accounting functions in manufacturing businesses.
Accurately managing accounting functions in a manufacturing business not only ensures legal compliance but also forms the foundation for all important economic decisions. Join MAN – Master Accountant Network as we delve into the characteristics and management methods of each core function below.
Cost accounting and production costing
This is the most important part, determining the profit margin of the business. To calculate correctly, accountants need to adhere to the following formula:
|
Total cost = Material cost + Labor cost + Manufacturing overhead |
In there:
- Direct material costs: Must be tracked according to production standards.
- Direct labor costs: These include the salaries and payroll deductions of workers directly involved in producing the product.
- General manufacturing overheads: Costs incurred in the factory such as machinery depreciation, electricity, water, and salaries for factory management staff.
Note: For ending work-in-progress costs, accurate assessment based on completion level is necessary to avoid distorting actual costs.
Inventory and materials accounting
In a manufacturing business, inventory includes not only finished goods but also raw materials, auxiliary materials, and semi-finished products. The inventory management process must be regularly compared with actual factory records. The flexible application of the weighted average cost or FIFO method, depending on the characteristics of the goods, is key to ensuring that the cost of goods sold accurately reflects market conditions.
Accounting for fixed assets and tools and equipment
Fixed assets in manufacturing businesses are often high-value machinery and equipment. Tracking their lifecycle and applying the correct depreciation method (straight-line or declining balance) helps businesses reinvest in a timely manner and take advantage of tax shield benefits.
Other accounting functions: Payments, accounts payable, payroll.
Although not directly involved in the factory, the payment and accounts receivable process is crucial to operations. A transparent accounts receivable process ensures uninterrupted input supply chains, while payroll accounting needs to be flexible between piece-rate wages (to encourage productivity) and time-based wages (to ensure stability).
Challenges and solutions for operational optimization
In reality, implementing accounting functions in manufacturing businesses involves more than just dividing tasks; it also faces numerous pressures from operations, technology, and legal compliance requirements. Without proper control, businesses are highly susceptible to cost discrepancies, material losses, or cash flow imbalances.
Common challenges in manufacturing businesses
However, effectively managing accounting functions in a manufacturing business is not a simple task. In practice, businesses often face numerous issues related to data, costs, control processes, and compliance pressure. The following challenges are common bottlenecks that directly affect the accuracy of cost accounting, operational efficiency, and the ability to optimize profits.
Lack of data synchronization between departments.
One of the biggest challenges is that data between warehouse, production, and accounting often doesn't match. If the warehouse department is slow to update the quantity of raw materials used, or if the factory doesn't accurately record actual production output, the entire cost report can be inaccurate.
It is difficult to control actual production costs.
Many businesses still apply outdated standards even though their production processes have changed. This leads to unplanned increases in material, labor, or general production costs without timely warning, reducing profit margins.
The pressure of processing large and continuous amounts of data.
Manufacturing businesses typically generate thousands of documents each month related to inventory receipts, shipments, material transfers, timekeeping, machinery depreciation, and cost allocation. If processed manually using Excel or separate software, accountants are prone to errors and waste significant time on reconciliation.
It is difficult to determine the cost of work-in-progress.
For businesses with multiple production stages, valuing work-in-process inventory at the end of the period is always a complex problem. Discrepancies in determining the completion rate can lead to the cost of goods sold being inflated or undervalued.
Tax and audit risks
When accounting figures and actual production data are inconsistent, businesses may face questioning from tax authorities regarding the reasonableness of input costs, material consumption standards, or depreciation of fixed assets.
Operational optimization solution
To ensure that accounting functions in manufacturing businesses operate efficiently and synchronously, businesses need to develop a management strategy that aligns with the digital transformation trend and the increasingly stringent cost control requirements. Below are key solutions to optimize operations, reduce errors, and improve financial management efficiency.
ERP applications integrate AI and real-time data.
Modern ERP systems enable direct connection between warehousing, production, purchasing, and accounting. Data is updated in real time, reducing manual errors and supporting cost traceability down to each stage of production.
Alongside the adoption of ERP and AI, many businesses are now also shifting to a new model. online accounting services The aim is to optimize personnel costs while still ensuring real-time data monitoring and remote operational control.
Standardize the document flow process.
Businesses need to establish a standardized process from creating warehouse release forms and confirming production quantities to approving payments. Standardization helps reduce instances of incomplete documents or overlapping entries.
Set flexible cost limits.
Material and labor standards need to be reviewed periodically in response to price fluctuations and changes in production technology. This is a crucial basis for accounting to analyze discrepancies and control production efficiency.
Strengthen inventory and periodic reconciliation processes.
Businesses should conduct inventory checks of materials, semi-finished products, and finished products on a monthly or quarterly basis, rather than just at the end of the year. Regular reconciliation helps detect losses or discrepancies in data early.
Strengthen internal controls and data access control.
Clearly defined access control in accounting and ERP software helps to limit fraud and improve the ability to access data editing history when errors occur or during internal audits.
Advanced cost calculation methods
To better clarify accounting practices in manufacturing businesses, the accounting department needs to understand the differences between the two most common costing methods:
- Order-based pricing: This method is applied to businesses that produce goods on a case-by-case basis (e.g., printing, shipbuilding). Here, costs are aggregated for each specific order. The complexity lies in allocating overhead costs to each order fairly.
- Process costing method: Applicable to businesses engaged in mass, continuous production (e.g., chemicals, textiles). The focus is on calculating the average cost per unit of product at each stage of the process.
The practical challenge: Many businesses today make the mistake of using outdated allocation methods (for example, allocating overhead costs only based on direct labor hours). By 2026, modern manufacturing businesses are shifting to activity-based costing to allocate costs according to actual activities, helping to determine the exact cost of each product line.
A real-world case study on the problem of allocating manufacturing overhead costs.
Situation: Company X manufactures electronic components. They use electricity costs as the primary basis for allocating overhead costs. However, revenue decreased while electricity costs increased.
- From an accounting perspective: Cost accountants found that the machinery was not operating optimally (running idle). If they relied solely on traditional accounting data, they would record an unreasonable increase in costs.
- Solution: Apply real-time data from IoT sensors on machinery to determine the actual running time of the machines. From this, accountants can adjust cost allocation, eliminate wasteful costs that do not create value, and thus arrive at a cost figure that is closer to market reality. This demonstrates that accounting functions in manufacturing businesses are shifting from a record-keeping role to an effective management role.
Frequently Asked Questions about Accounting Procedures in Manufacturing Businesses
A typical manufacturing business will include key functions such as cost accounting, materials and inventory accounting, fixed asset accounting, payroll accounting, accounts payable accounting, revenue accounting, and tax accounting.
The choice of cost calculation method depends on the actual production model. Mass production businesses typically apply process-based or standard-based costing methods. Meanwhile, businesses producing on a job-by-job or contract basis are usually better suited to job-based or contract-based costing methods. The important thing is that the chosen method accurately reflects the nature of the costs incurred and ensures consistency across accounting periods.
This is a common problem in many manufacturing businesses, especially when management is done manually using Excel or when processes are not synchronized. To minimize discrepancies, businesses need to establish a unified inventory, shipping, and stocktaking process, update data in real time, and conduct periodic inventory checks. Integrating ERP software between warehouse, production, and accounting also significantly reduces data discrepancies.
Yes. Tracking and evaluating work-in-process inventory at the end of the period is crucial for accurately determining the cost of goods sold and actual profit. Without accurately assessing the completion level of work-in-process inventory, businesses may incorrectly record production costs during the period, leading to inaccurate financial reporting and impacting tax obligations.
Even small-scale manufacturing businesses should clearly define responsibilities for each task to ensure data control and mitigate risks. In cases of limited staff, a business can assign one accountant to handle multiple tasks, but a clear reconciliation and approval process is still necessary to avoid overlapping or errors in operations.
What accounting functions does a manufacturing business need to organize?
Which cost accounting method should manufacturing businesses adopt?
How can we control discrepancies between inventory and accounting figures?
Is it mandatory for production accountants to track work-in-process inventory at the end of the period?
Do small businesses need to separate their accounting functions?
Conclude
Synchronizing accounting functions within a manufacturing business is key to achieving sustainability and financial efficiency. In 2026, when digital transformation becomes mandatory, investing in professional software systems and a team of highly skilled professionals will be a strategic priority for all manufacturing businesses.
In a context where businesses increasingly prioritize cost optimization and financial data standardization, choosing a reliable provider becomes crucial. accounting services Reputable and experienced accounting firms in the manufacturing sector, such as MAN – Master Accountant Network, will help businesses build a systematic accounting system, mitigate risks, and improve long-term financial management efficiency.
Contact MAN – Master Accountant Network For free consultation and prompt support!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- Email: man@man.net.vn
Content production by: Mr. Le Hoang Tuyen – Founder and CEO of MAN – Master Accountant NetworkCPA Vietnam auditors with over 30 years of experience in accounting, auditing, and financial consulting.






