
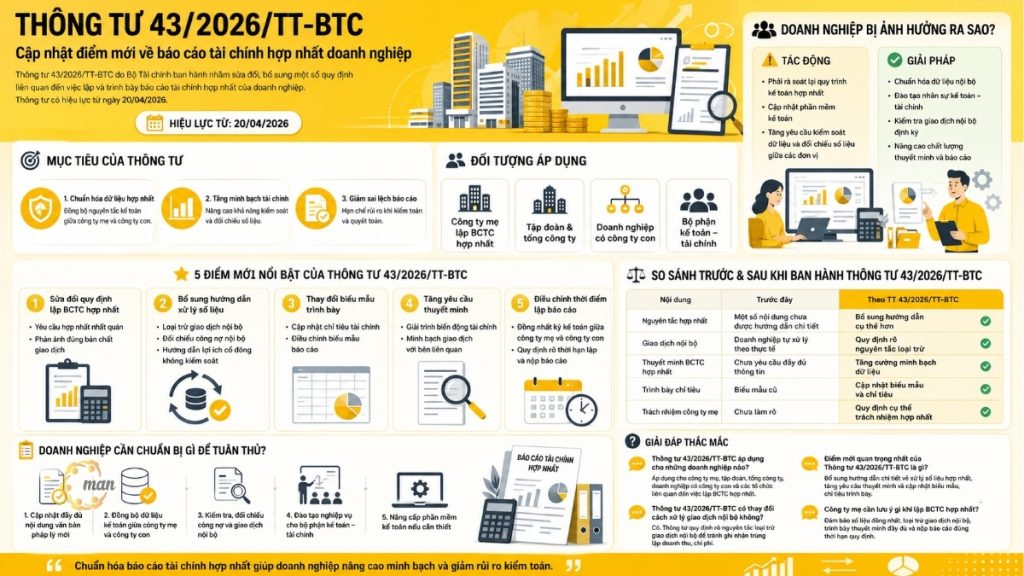
Circular 43/2026/TT-BTC The Ministry of Finance issued this document to amend and supplement certain regulations related to consolidated financial statements of enterprises. This document quickly attracted attention from accountants, auditors, as well as businesses with subsidiaries, economic groups, and entities required to prepare consolidated financial statements.
In the context of increasing demands for financial data transparency, updating Circular 43/2026/TT-BTC not only helps businesses comply with legal regulations but also supports the improvement of internal financial management quality. The changes in the circular are considered to have a direct impact on the process of preparing, presenting, and disclosing consolidated financial statements.
This article will provide a comprehensive analysis of the noteworthy content, clarifying the new points, scope of application, and important considerations that businesses need to be aware of.
Information regarding the issuance of Circular 43/2026/TT-BTC
Circular 43/2026/TT-BTC is a document issued by the Ministry of Finance to amend and supplement regulations related to the preparation and presentation of consolidated financial statements of enterprises.
According to the document, Circular 43/2026/TT-BTC focuses on updating several accounting principles, providing guidance on handling consolidated data, and adjusting requirements for presenting financial information. This is considered a necessary adjustment to align with current business practices.
The circular will take effect from April 20, 2026. Therefore, businesses need to proactively review their accounting processes and financial data systems to ensure timely implementation.
Objectives of Circular 43/2026/TT-BTC
The issuance of this Circular aims at achieving several important objectives in the management of corporate finance.
First, the Circular helps to improve the legal framework related to consolidated financial reporting. During the implementation of the old regulations, many businesses encountered difficulties in handling data between parent and subsidiary companies, especially in internal transactions or cross-investments. Therefore, Circular 43/2026/TT-BTC is expected to resolve these issues.
Furthermore, this document contributes to enhancing the transparency and consistency of financial information. When businesses apply the same consolidation principles and data presentation standards, financial reports will more accurately reflect the overall performance of the entire group.
In addition, Circular 43/2026/TT-BTC also supports management agencies, investors, and auditing units in easily comparing data and evaluating the performance of businesses.
The subjects to which Circular 43/2026/TT-BTC applies are those specified in Circular 43/2026/TT-BTC.
Applies to:
- The parent company must prepare consolidated financial statements.
- Economic groups and corporations have subsidiary units.
- The company has subsidiaries.
- Organizations and individuals involved in the preparation and presentation of consolidated financial statements.
Businesses with multiple subsidiaries should pay particular attention, as changes in Circular 43/2026/TT-BTC may directly impact their internal accounting processes.
Key new points of Circular 43/2026/TT-BTC
The revised regulations are considered to have made significant adjustments to the preparation and presentation of consolidated financial statements. These revisions focus not only on accounting techniques but also on enhancing transparency, data consistency, and the ability to control financial information between parent and subsidiary companies. Below are some of the key new points that businesses should pay particular attention to during implementation.
Amendments to regulations on the preparation of consolidated financial statements.
One of the most notable aspects of Circular 43/2026/TT-BTC is the adjustment of regulations related to the preparation of consolidated financial statements.
Accordingly, businesses need to ensure that data consolidation is carried out consistently between the parent company and its subsidiaries. Financial indicators must fully reflect the nature of transactions rather than merely recording them formally.
The circular also clarifies the parent company's responsibility in aggregating financial data. This helps to reduce discrepancies in figures between subsidiary units.
In addition, businesses need to review their data verification process before releasing consolidated financial statements to ensure accuracy and transparency.
The updated regulations have left many businesses unable to adapt, which is why this solution is needed. hire an accountant to prepare financial statements. This is the most optimal approach to ensure that data is processed accurately and correctly, and to minimize risks during auditing.
Additional guidance on handling consolidated data.
Circular 43/2026/TT-BTC provides additional detailed guidance related to the processing of consolidated data.
In particular, intercompany transactions between companies within the same group must be appropriately excluded to avoid double-recording of revenue or expenses. Internal receivables and payables also need to be fully reconciled before preparing the report.
Regarding the interests of non-controlling shareholders, the Circular requires businesses to clearly state the basis for determining and allocating after-tax profits.
In addition, the recording of investments in subsidiaries has been given more specific guidance to ensure consistency across reports.
Changes to the format and presentation criteria
Circular 43/2026/TT-BTC also updates some forms related to consolidated financial statements.
Some financial indicators are added or adjusted to more accurately reflect the company's performance. This requires the accounting department to update its accounting forms and software to avoid errors.
Businesses also need to pay attention to presenting material items in accordance with the requirements of Circular 43/2026/TT-BTC in order to increase the transparency of financial information.
New regulations on disclosure requirements for consolidated financial statements.
Besides revising the forms, Circular 43/2026/TT-BTC also strengthens the requirements for the explanatory notes to consolidated financial statements.
Businesses need to clearly present the accounting policies applied, consolidation methods, and significant transactions between related parties. Adding explanatory information provides regulators and investors with a better basis for assessing the accuracy of the financial statements.
In addition, the Circular requires businesses to clearly explain any significant changes in revenue, expenses, or assets during the period.
Adjustments related to the timing of preparing consolidated financial statements.
According to Circular 43/2026/TT-BTC, businesses need to ensure consistency in accounting periods between the parent company and its subsidiaries when consolidating financial statements.
In case of discrepancies in accounting periods, businesses must make appropriate adjustments and provide specific explanations in the explanatory notes.
In addition, the deadlines for preparing and submitting consolidated financial statements must be strictly adhered to in order to avoid the risk of administrative violations.
How does Circular 43/2026/TT-BTC affect businesses?
The issuance of Circular 43/2026/TT-BTC not only impacts the process of preparing consolidated financial statements but also directly affects financial management, data control, and internal accounting practices of businesses. In particular, parent companies, conglomerates, and businesses with multiple subsidiaries will need to review their entire consolidation process to ensure compliance with the new regulations. Below are some key impacts that businesses should pay special attention to.
Review the consolidated accounting process.
After the Circular officially comes into effect, businesses should review their entire financial statement consolidation process.
This includes checking accounting data systems, reconciling internal accounts payable, and standardizing reporting forms among member units. If data control processes are not synchronized, businesses are very likely to encounter discrepancies when consolidating data.
Impact on the accounting and finance department
Circular 43/2026/TT-BTC sets higher requirements for corporate accounting and finance staff.
Personnel in charge need to have a thorough understanding of consolidation principles, methods for eliminating intercompany transactions, and how to present items according to the new regulations.
In many cases, businesses may need to retrain staff or update accounting software to meet the requirements.
For businesses that do not have personnel specializing in financial statement consolidation, the solution is... hire chief accountant It can assist in controlling financial data, reviewing accounting systems, and ensuring compliance with regulations.
Impact on the auditing of financial statements.
The changes in the Circular also directly impact the auditing of financial statements.
The auditing firm will need to conduct a more thorough examination of the exclusion of intercompany transactions, reconcile figures between the parent company and its subsidiaries, and assess the adequacy of the disclosures.
Businesses with inconsistent data systems will face many difficulties during audits and in explaining their financial data.
What preparations do businesses need to make to comply with Circular 43/2026/TT-BTC?
To implement this effectively, businesses should:
- The content of the new legal document has been fully updated.
- Organize professional training for the accounting department.
- Review the financial data system.
- Synchronize data recording processes between the parent company and the subsidiary.
- Upgrade your accounting software if necessary.
Early preparation will help businesses minimize the risk of errors and avoid being caught off guard when the circular officially comes into effect.
If a business does not have a dedicated team or sufficient resources to manage consolidated data, then using full accounting service This will help optimize accounting processes, reduce the risk of errors, and ensure compliance with regulations as stipulated in Circular 43/2026/TT-BTC.
Comparing the changes before and after the issuance of Circular 43/2026/TT-BTC
The changes focus not only on the principle of data consolidation but also on adjusting the presentation of information, handling of internal transactions, and the responsibilities of the parent company in the reporting process. The table below summarizes the notable changes before and after the Circular was issued, helping businesses and accounting departments easily track and proactively prepare for the application of the new regulations.
| Content | Previous regulations | Circular 43/2026/TT-BTC |
| Principle of integration | Some content has not been explained in detail. | Add more specific instructions. |
| Insider trading | Businesses handle things themselves based on the actual situation. | Clearly define the exclusion principle. |
| Notes to the consolidated financial statements | Not all information has been requested yet. | Enhancing data transparency |
| Present the criteria | Old form | Update forms and criteria |
| Responsibilities of the parent company | Not yet clarified | Specific regulations regarding consolidation responsibilities. |
The comparison table above shows that the adjustments are not only technical accounting modifications but also aim for comprehensive standardization in the preparation and presentation of consolidated financial statements. These new changes help businesses improve data transparency, reduce errors during data consolidation, and enhance the comparability between the parent company and its subsidiaries. Simultaneously, the addition of indicators such as "Goodwill" or "Non-controlling shareholder interests" helps financial statements more accurately reflect the nature of the business's operations in accordance with modern governance requirements.
The significance of the changes in Circular 43/2026/TT-BTC
The amendments in the Circular bring many benefits to businesses:
- Standardizing the consolidation process helps reduce the risk of financial data discrepancies. This is a crucial factor for businesses with multiple subsidiaries.
- Requiring transparency also helps increase the credibility of financial reports for investors and partners.
- Improving the quality of financial management and supporting businesses in effectively controlling internal operations.
Important notes when applying Circular 43/2026/TT-BTC
The implementation of Circular 43/2026/TT-BTC is not merely about updating legal documents; it also requires businesses to comprehensively review their accounting processes, financial data, and methods for preparing consolidated financial statements. During practical implementation, businesses need to pay particular attention to the effective date, the consistency of data among member units, and the information transparency requirements under the new regulations. Below are some important points that businesses should not overlook when applying the regulations:
- Timely update: Circular 43/2026/TT-BTC takes effect from April 20, 2026. Businesses need to proactively update to the new regulations to avoid misapplying the document. Delays in updating may lead to errors in the preparation of consolidated financial statements.
- Verify data consistency between parent and subsidiary companies: One common problem when consolidating reports is the lack of synchronization of data between member units. Therefore, businesses need to carefully check internal transactions, reconcile accounts payable and receivable, and agree on accounting principles before consolidating data.
- Preparing notes to consolidated financial statements: The notes to the financial statements need to be presented fully and clearly. Businesses should focus on explaining material items, related-party transactions, and significant changes during the accounting period.
Frequently Asked Questions about Circular 43/2026/TT-BTC
Circular 43/2026/TT-BTC applies to parent companies, economic groups, corporations, and enterprises with subsidiaries that are required to prepare consolidated financial statements in accordance with current accounting laws. In addition, entities involved in the compilation, verification, and presentation of consolidated financial data are also subject to the Circular's regulations.
A key highlight of Circular 43/2026/TT-BTC is the amendment and clarification of the principles for preparing consolidated financial statements, particularly regarding the handling of intercompany transactions, the exclusion of intercompany revenue and expenses, and the requirement for transparency in explanatory information.
Yes. One of the key aspects of Circular 43/2026/TT-BTC is to strengthen guidance on handling internal transactions between companies within the same system. Revenue, expenses, liabilities, or unrealized profits arising internally need to be appropriately excluded when consolidating financial statements. This helps avoid double recording and accurately reflects the actual financial situation of the entire enterprise.
The parent company needs to pay particular attention to standardizing accounting policies among its subsidiaries, reconciling internal liabilities, and verifying transactions occurring within the same system. In addition, the company needs to maintain complete records explaining consolidation entries, allocation of non-controlling shareholder interests, and adjustments to figures arising during the period to facilitate audits and inspections when necessary. Which businesses are covered by Circular 43/2026/TT-BTC?
What is the most important new point of Circular 43/2026/TT-BTC?
Does Circular 43/2026/TT-BTC change the way internal transactions are handled?
What should the parent company keep in mind when preparing consolidated financial statements?
Conclude
Circular 43/2026/TT-BTC has finalized regulations related to the preparation and presentation of consolidated financial statements in enterprises. The new amendments and additions not only enhance the transparency of financial data but also contribute to standardizing the consolidation process between parent companies and subsidiaries.
Timely updates will help businesses minimize the risk of errors in financial reporting, while also improving internal control and better meeting the requirements of regulators, auditors, and investors. In particular, corporate businesses need to proactively review their accounting processes, synchronize data, and enhance the capabilities of their finance teams to ensure compliance with the new regulations.
For any questions or concerns, please contact MAN – Master Accountant Network for prompt support and expert advice.
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- Email: man@man.net.vn
Content production by: Mr. Le Hoang Tuyen – Founder and CEO of MAN – Master Accountant NetworkCPA Vietnam auditors with over 30 years of experience in accounting, auditing, and financial consulting.






