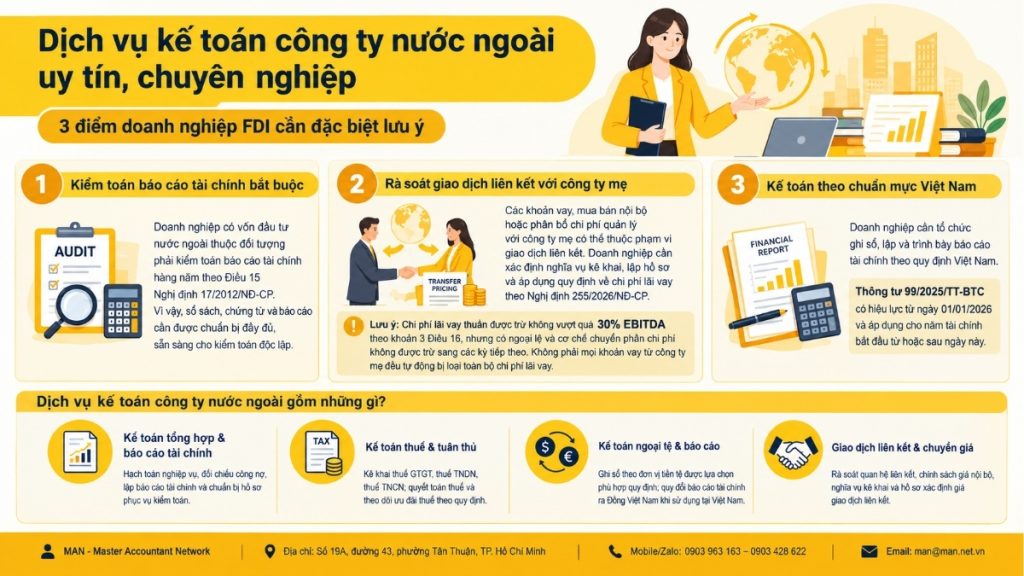
Accounting services for foreign companies are not simply about bookkeeping and submitting reports on time. Because they are foreign companies, most investors lack the time and personnel to continuously update their knowledge of Vietnam's accounting, tax, and investment laws, which change frequently and differ significantly from practices in their home countries. This lack of understanding not only risks administrative penalties but also causes businesses to lose legitimate rights they should be entitled to when operating in Vietnam, from the right to repatriate profits on time and the right to carry forward excess interest expense, to the right to self-declare tax returns instead of being assessed by the tax authorities. This article outlines the specific legal basis, scope of work, and criteria for selecting an accounting service provider for foreign companies, helping business owners and chief accountants make the right decisions from the outset.
Why do foreign companies in Vietnam need specialized accounting services?
Foreign-invested enterprises operate within a more complex legal framework than domestic enterprises in three respects:
- Accounting system applied;
- Mandatory audit obligation;
- And cross-border transactions with the parent company or affiliated parties abroad.
The problem lies in the fact that, precisely because they are foreign companies, the management and accounting teams in Vietnam often do not come from the Vietnamese legal system, and therefore lack the natural ability to react to deadlines, conditions, and exceptions stipulated in legal documents. This is why accounting services for foreign companies always require a higher level of expertise than a regular accounting service.
Three common legal hurdles when foreign companies operate their own accounting departments.
Firstly, there are differences in accounting standards. Foreign investors are familiar with IFRS or their own domestic accounting standards, while Vietnamese law requires the preparation of financial statements according to the Corporate Accounting System issued under... Circular 99/2025/TT-BTC (Effective from January 1, 2026, applicable to fiscal years beginning on or after January 1, 2026, replacing Circular 200/2014/TT-BTC). Simultaneous conversion between the two reporting systems without a dedicated team can easily lead to data discrepancies.
Secondly, there are language barriers and deadlines for filing. Tax returns and financial reports submitted to Vietnamese state management agencies are required to be in Vietnamese (with possible translations), while the parent company requires bilingual reports on internal management deadlines. Businesses without accounting services for foreign companies to support both reporting streams often experience delays at either end.
Thirdly, there is a shortage of qualified personnel. According to the Accounting Law, the chief accountant must meet standards regarding qualifications, certifications, and experience. Newly established FDI enterprises, with small staff sizes, often cannot immediately recruit for this position and are forced to consider outsourcing.
Foreign companies lose their legal rights when they are unfamiliar with Vietnamese accounting and tax regulations.
This is a less-discussed consequence, but the actual damage often outweighs administrative fines: foreign companies forfeit the rights granted to them by Vietnamese law simply because they are unaware of or fail to meet the required procedures.
- Loss of the right to repatriate profits on time: According to Circular 186/2010/TT-BTC, foreign investors are only allowed to repatriate profits after submitting audited financial statements and corporate income tax returns to the directly managing tax authority, notifying the tax authority of the profit repatriation, and having no accumulated losses after carrying forward losses as prescribed. Foreign companies that are unaware of this procedure often submit audited reports late or omit the notification step, causing profits that should have been repatriated to the parent company in the current year to be held up until the next period.
- Loss of carryforward of interest expense exceeding the 30% EBITDA threshold: According to clause 3 Article 16 of Decree 255/2026/ND-CPThe portion of interest expense exceeding the threshold arising from the parent company's loan is allowed to be deferred and deducted gradually in subsequent periods, but the continuous transition period cannot exceed 5 years and only applies to the period in which the related-party transaction occurs. Businesses that do not properly track this timeframe, especially foreign companies accustomed to using their own fiscal calendar and accounting terminology, may lose their right to deduction entirely, even if, in principle, it is still within the allowed period.
- Loss of the right to self-declare tax returns, replaced by tax authority's assessment: According to Law on Tax Administration No. 108/2025/QH15 (Effective from July 1, 2026, replacing Law No. 38/2019/QH14 on Tax Administration), taxpayers are obligated to demonstrate the analysis, comparison, and selection of the method for determining transfer pricing. Foreign companies that fail to provide this documentation will lose the right to independently determine their costs and transaction prices and must accept the assessment imposed by the tax authorities, which is often more unfavorable than the figures calculated by the company itself.
Risks of choosing the wrong accounting service for a foreign company.
Choosing an incompetent accounting firm for a foreign company leads to three direct consequences:
- The financial statements were subject to a qualified opinion from an independent auditor.
- Tax returns were reassessed during an audit.
- And more seriously, the business falls into a predicament. Violation of accounting regulations They may be subject to administrative penalties under Decree 41/2018/ND-CP (amended and supplemented by Decree 132/2026/ND-CP, effective from May 21, 2026), and this may even affect their eligibility for renewing their investment certificate.
For foreign companies, the majority of these violations do not stem from intent, but from a lack of prior warning about the specific deadlines and conditions of Vietnamese law.
Reference: How to determine the salary used for calculating social insurance contributions for foreign workers.
Mandatory legal basis for using accounting services for foreign companies.
Choosing an accounting service for a foreign company is not a purely commercial decision, but involves many specific legal obligations that business owners need to understand before signing a contract. The three obligations below are three points that foreign companies, not originating from the Vietnamese legal system, often overlook or misunderstand, and are also the three points that tax authorities and independent auditors check first.
Independent audits are mandatory for businesses with foreign investment.
According to Decree 17/2012/ND-CP guiding the Law on Independent Auditing, enterprises with foreign investment capital are required to have their annual financial statements audited. This is a fundamental difference compared to small-scale domestic enterprises. Therefore, full accounting service For foreign companies, the system must be designed so that records, documents, and books are always ready for independent audits, rather than just meeting the minimum requirements of the tax authorities.
The obligation to declare related-party transactions when borrowing capital from a foreign parent company.
Most foreign companies in Vietnam engage in transactions involving borrowing, internal sales, or the allocation of management expenses with their parent companies abroad. These are considered related-party transactions according to Decree 255/2026/ND-CP on tax management for enterprises with related-party transactions (effective from July 1, 2026, replacing Decree 132/2020/ND-CP and Decree 20/2025/ND-CP). Therefore, the enterprise must... Prepare a Transfer Pricing Documentation File. and comply with the threshold for net interest expense not exceeding 30% EBITDA as stipulated in Clause 3, Article 16 of this Decree. Proper accounting services for foreign companies must include the capacity to review this obligation, because an unreported loan from the parent company could result in the entire related interest expense being disallowed during corporate income tax settlement.
What services are included in accounting services for foreign companies?
A comprehensive accounting service package for a foreign company should cover the following four groups of tasks, rather than just simple bookkeeping.
General accounting and financial reporting according to Vietnamese standards.
This includes accounting for monthly transactions, reconciling accounts payable and receivable, preparing annual financial statements in accordance with Circular 99/2025/TT-BTC applicable to fiscal years from 2026, and preparing explanatory notes to the financial statements for independent audits. For FDI enterprises, the explanatory notes regarding related parties and transactions with the parent company need to be presented transparently from the beginning of the fiscal year, not waiting until the audit to be added.
Tax accounting and compliance with filing obligations.
This includes filing value-added tax returns, quarterly provisional corporate income tax returns, corporate income tax final settlements, and personal income tax returns for foreign employees, as well as monitoring tax incentives enjoyed by FDI enterprises according to their investment registration certificates (tax exemptions and reductions based on geographical areas or investment-encouraged sectors).
Accounting in foreign currency and conversion of bilingual reports.
Accounting law allows accounting units whose primary transactions are in a foreign currency to choose their accounting currency, but financial statements submitted to state management agencies in Vietnam must still be converted to Vietnamese Dong. Accounting services for foreign companies need to handle two processes simultaneously: maintaining records in the currency used for accounting and preparing reports converted to the correct exchange rate at the time of transaction, avoiding exchange rate discrepancies that may be miscalculated when consolidating reports with the parent company.
Providing advice on related-party transactions and transfer pricing for foreign-owned companies.
This is the most significant differentiating factor between a professional accounting service for a foreign company and a general accounting service: reviewing the ownership structure to identify related-party relationships, developing internal transaction pricing policies consistent with the arm's length principle, and preparing transfer pricing documentation within the deadline for filing tax returns.
5 criteria for choosing a reputable accounting service provider for a foreign company.
Legal capacity and professional certification
Verify the Certificate of Eligibility for Accounting Services and the Accounting Practice Certificate of the person directly responsible for the application. This is a mandatory requirement, not a bonus.
Experience in handling FDI applications and cross-border transactions.i
A firm that has previously handled accounting services for foreign companies in various investment countries (Japan, Singapore, China, Malaysia, etc.) will have a thorough understanding of the specific reporting requirements of each parent company, as well as how to present related-party transaction documents in accordance with international practices.
The ability to collaborate with independent auditors and tax authorities.
Since FDI businesses are required to undergo annual audits, accounting service providers for foreign companies need to proactively work directly with auditors, explain data, and make timely adjustments before the official audit report is issued, instead of leaving the business to handle it on its own.
Financial data security procedures
Accounting data from foreign parent companies is often highly confidential (internal cost of goods sold, foreign expert salary policies). Service providers need to have clear access control procedures and confidentiality commitments in the contract.
The ability to provide long-term consulting, not just handling emerging issues.
A good accounting firm for foreign companies will proactively warn businesses of potential risks: approaching audit deadlines, nearing the threshold for deductible interest expenses, or when tax policies change, instead of only reacting when requested by the tax authorities.
Reference price list for accounting services for foreign companies.
Accounting service price list For foreign companies, the budget is structured into packages, depending on the scale of the documentation generated and the complexity of the related-party transactions. The table below is for reference only, to help businesses estimate their budget before working directly with a consulting firm.
| Service package | Suitable candidates | Scope of work | Reference fee |
| Basic | Representative offices, newly established companies, with no or low revenue generated. | Record keeping, declare business license tax, and report on business operations. | 3,000,000 – 5,000,000 VND |
| Standard | FDI companies engaged in trade and services generate consistent revenue and do not have complex related-party transactions. | General accounting, VAT and corporate income tax filing on a quarterly basis, and support for annual tax settlement. | 6,000,000 – 12,000,000 VND |
| Advanced | FDI companies are manufacturing companies that borrow capital or conduct transactions with foreign parent companies. | The complete Standard package includes review of related-party transactions and support for working with independent auditors. | 12,000,000 – 25,000,000 VND |
| Specialized FDI | Multinational corporations with numerous related-party transactions require bilingual reporting to the parent company. | The complete Advanced package includes: preparation of related-party transaction pricing documentation, consultation on 30% EBITDA threshold, and periodic bilingual reports. | A separate quote will be provided based on the actual project details. |
Note: The above price list is for reference only; actual fees may vary depending on the number of documents generated monthly, the number of related-party transactions to be tracked, and the specific bilingual reporting requirements of each business. For an accurate quote, please contact MAN for consultation and support.
The advantages of outsourcing accounting services compared to building your own in-house accounting department.
For new small and medium-sized FDI enterprises entering the Vietnamese market, the following approach is recommended: outsource accounting services It is generally more advantageous to set up an in-house accounting department in three aspects:
- Lower fixed costs: No need to pay salaries, insurance, or training for a full accounting department during the period when the business has not yet reached a stable revenue scale.
- Reducing the risk of sudden employee turnover: The resignation of a chief accountant or general accountant during the accounting period is a serious operational risk for businesses with only 1-2 accounting staff; outsourced accounting services for foreign companies completely eliminate this risk thanks to a backup team.
- Gain immediate access to expertise in related-party transactions and auditing: Instead of training internal staff from scratch, businesses can have a team already handling many similar cases.
The process of providing accounting services to foreign companies.
The service deployment process at MAN – Master Accountant Network:
- Step 1 – Current Status Survey: Review the investment registration certificate, ownership structure, loan agreement with the parent company, and current accounting records (if the business is already operational).
- Step 2 – Establishing the accounting system and classifying related-party transactions: Determine the applicable accounting method, the currency used for recording, and identify the related-party relationships that need to be tracked separately.
- Step 3 – Operating the accounting system and periodic declarations: Monthly accounting, value-added tax declaration, quarterly provisional corporate income tax payment.
- Step 4 – Prepare annual financial statements and coordinate with independent auditors: Prepare financial statements and explanatory notes, and work with auditors to ensure the audit report is issued on time.
- Step 5 – Tax settlement and completion of related-party transaction documentation: Submit the corporate income tax return, related-party transaction appendix, and archive supporting documents for future audits.
Conclude
Ultimately, the majority of risks and losses to the rights of foreign companies in Vietnam do not stem from intentional wrongdoing, but from the gap between the legal system they are familiar with and the Vietnamese legal system, where each condition for profit transfer, each deadline for the transfer of interest expense, and each obligation to declare related-party transactions is specifically stipulated in a separate document and can change annually. Accounting services for foreign companies cannot operate on a mass accounting service model, as they are tied to three specific obligations:
- Comply with Vietnamese accounting regulations while reporting to the parent company;
- An independent annual audit is mandatory.
- And declare related-party transactions when there is a cross-border loan relationship or expense allocation.
Businesses that choose the right accounting service provider for their foreign company from the very beginning of their operations will retain all their legal rights, instead of discovering they have lost those rights when it is too late to rectify the situation.
If your business is considering outsourcing or wants to review its current accounting system, MAN's team of experts is ready to assist. accounting consulting services Suitable for the specific industry and scale of investment capital of the enterprise.
Contact MAN – Master Accountant Network For expert advice and support!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyenn – Founder & CEO of MAN – Master Accountant NetworkHe is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions about Accounting Services for Foreign Companies
Is it mandatory for foreign companies to hire accounting services?
Outsourcing is not mandatory, but businesses must have a qualified chief accountant as required by the Accounting Law. If there is no in-house qualified personnel, hiring accounting services for a foreign company from a unit holding a Certificate of Eligibility to conduct accounting services is a legal and common option.
Are foreign-invested companies required to have their financial statements audited?
Yes. Foreign-invested enterprises are required to have their annual financial statements audited according to regulations on independent auditing, regardless of their revenue or total assets.
Can accountants working for foreign companies record transactions in a foreign currency?
An entity whose primary business is conducted in a foreign currency may choose its accounting currency in accordance with the Accounting Law, but financial statements submitted to state management agencies in Vietnam must still be converted into Vietnamese Dong.
Does borrowing from a foreign parent company affect the deductibility of interest expenses?
Yes. Loans from the parent company are typically identified as related-party transactions, in which case the net interest expense is subject to a limit of not exceeding 30% EBITDA as stipulated in Clause 3, Article 16 of Decree 255/2026/ND-CP and must be declared in the Related-Party Transaction Pricing Documentation.
Why are foreign companies more likely to lose their rights than domestic businesses when it comes to accounting practices?
Because foreign companies do not operate under the Vietnamese legal system, they often lack understanding of the conditions and procedures associated with their rights: for example, the right to repatriate profits under Circular 186/2010/TT-BTC requires the submission of audited reports and notification to the tax authorities in the correct order, or the right to carry forward interest expense exceeding the 30% EBITDA threshold under Decree 255/2026/ND-CP is only valid if the company maintains proper accounting records for the five-year period. Omitting even one condition results in the loss of rights, even if the transaction is entirely legal.