
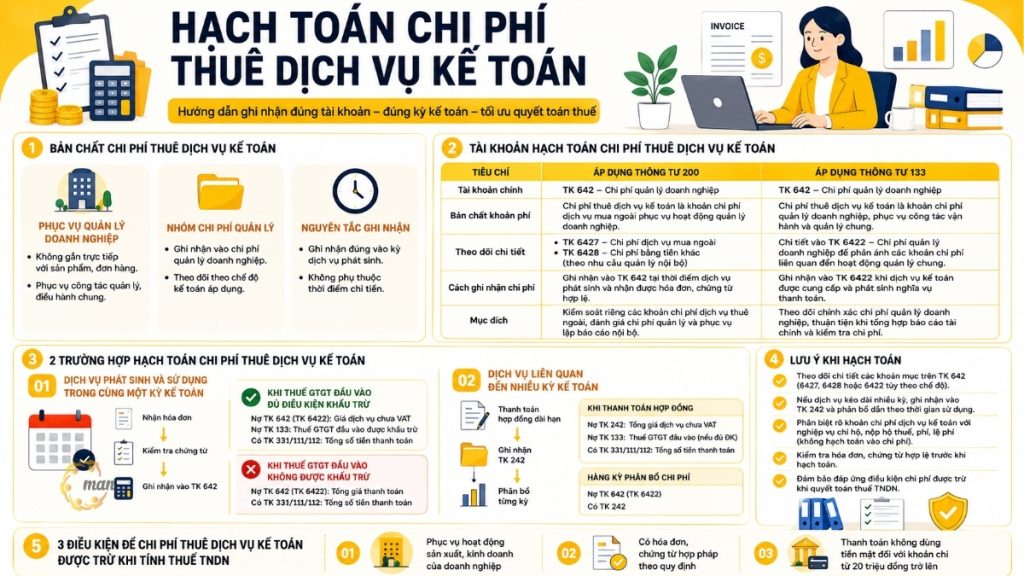
Proper accounting of accounting service fees is a mandatory requirement for all businesses using tax agents or outsourced accounting services. Based on... Circular 200/2014/TT-BTC and Circular 133/2016/TT-BTCThis expense is recorded as a business management expense, but the specific account and journal entry vary depending on whether the service is incurred in one or multiple periods. This article provides detailed guidance on each case, along with notes on value-added tax (VAT) and the conditions for deductible expenses when settling corporate income tax (CIT).
Understanding the true nature of accounting service costs
Before delving into the accounting techniques, business accountants need to correctly identify the nature of the expense. This could be an expense paid to a tax agent, an individual, or accounting services company It is an expense used for the general management and operation of the business.
This expense is not directly tied to a specific product or order, but serves to meet the legal tax and accounting obligations of the entire entity.
Because accounting services are business management expenses, they are recorded under the management expense category and adhere to the accrual accounting principle, meaning the expense must be recognized in the period in which the service is actually incurred and used, regardless of when the payment is made.
Accounting account for the cost of hiring accounting services.
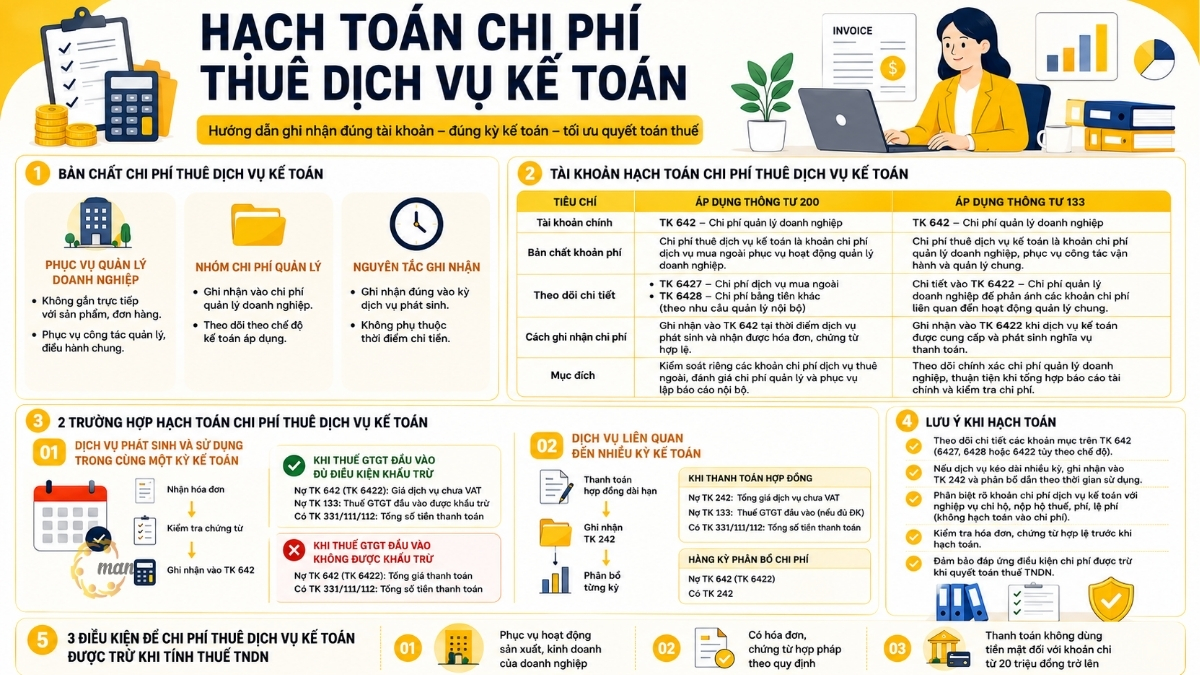
To ensure proper accounting cost of hiring accounting services To comply with regulations, businesses need to accurately determine the accounting system they are applying. Depending on whether Circular 200/2014/TT-BTC or Circular 133/2016/TT-BTC is applied, the accounts for recording expenses differ in classification and detailed tracking. Specifically, businesses can refer to the guidance below to choose the appropriate accounting accounts:
| Criteria | Applying Circular 200 | Applying Circular 133 |
| User account | Use account 642 – Business management expenses. | Use account 642 – Business management expenses. |
| The nature of the fee | The cost of hiring accounting services is considered an outsourced service expense for business management operations. | The cost of hiring accounting services is considered a business management expense, serving the overall operation and management of the business. |
| Account details | Businesses can create detailed accounts (account 642) to manage each expense item. For example:
Account 627 – Outsourced service costs: Tracks expenses for outsourced services such as accounting services, tax consulting, legal consulting, etc. Account 6428 – Other cash expenses: Can be used to track other administrative expenses as needed for internal management. |
Details should be entered into account 6422 – Business Management Expenses to reflect expenses related to the general management activities of the business. |
| How to record expenses | Record the transaction in account 642 – Business management expenses at the time the service is rendered and the business receives a valid invoice or supporting document. | Record the transaction in account 6422 – Business management expenses when accounting services are provided and payment obligations arise. |
| Example of accounting entry when hiring accounting services during the period. | When receiving an invoice for accounting services:
Debit Account 6427 – Outsourced service fees (excluding VAT) Debit Account 1331 – Deductible VAT (if eligible) Account 331 – Accounts Payable to Suppliers (total payment amount) Or you can use account 111 or 112 if paying immediately. |
When receiving an invoice for accounting services:
Debit Account 6422 – Business Management Expenses (excluding VAT) Debit Account 1331 – Deductible VAT (if eligible) Account 331 – Accounts Payable to Suppliers (total payment amount) Or you can use account 111 or 112 if paying immediately. |
| Purpose | It helps businesses control their outsourced service costs, evaluate management expenses, and prepare internal reports. | It helps businesses accurately track business management costs, making it convenient for compiling financial reports and auditing expenses. |
| Notes on accounting | If a business signs a long-term accounting service contract (e.g., an annual contract), it should consider recording it in account 242 – Prepaid Expenses and allocating it gradually over the service period. | Similarly, if accounting service fees relate to multiple accounting periods, they should not be recorded entirely in account 6422 but should be allocated through account 242 – Prepaid expenses. |
Therefore, regardless of the accounting method applied, the core principle when accounting for accounting service fees remains to include the service value in the management expense group. The key determining factor in the accounting technique is whether the service is provided within a single accounting period or spans multiple periods.
Cases for accounting for the cost of hiring accounting services.
Accounting for accounting service fees depends not only on the value of the service but also on the timing of the service and the duration of its use by the business. Depending on whether the service is completed within a single accounting period or extends over multiple periods, accountants will choose the appropriate recording method to ensure that the cost is reflected correctly in the period, accurately reflects its nature, and complies with accounting principles.
Typically, the cost of hiring accounting services will be handled in two ways:
- Services that arise and are used within the same accounting period.
- This service relates to multiple accounting periods.
Services that arise and are used within the same accounting period.
This is the simplest and most common case, for example, a business. hire an accountant to prepare tax reports. On a monthly or quarterly basis, invoices are issued within the period of use. Upon receiving a valid invoice and supporting documents from the supplier, the full value of the service will be recorded directly as an administrative expense for that period.
When input VAT is eligible for deduction
In cases where a business declares taxes using the deduction method and the invoices meet the requirements, the accountant separates the VAT portion for tracking. The journal entry is as follows:
- Debit Account 642 (Account 6422): Service price excluding VAT
- Debit Account 133: Input VAT that is deductible
- Account 331: Total amount payable (if still owed to suppliers)
- Or, Account 111, 112: Total amount if payment is made immediately.
When input VAT is not deductible
If the input VAT is not eligible for deduction, this amount is not recorded in account 133 but is added to the cost. In that case, the accounting for accounting service fees is done as follows:
- Debit Account 642 (Account 6422): Service price includes the non-deductible VAT portion.
- Account 331: Total amount payable (if not yet paid)
- Or, for accounts 111 and 112: the total amount (if already paid).
When making payments to suppliers
In cases where the debt was previously recorded through account 331, at the time of payment, the accountant will reflect:
- Debit Account 331: Amount paid to the service provider.
- Accounts 111 and 112 represent amounts disbursed in cash or via bank transfer.
Services related to multiple accounting periods.
In fact, quite a few businesses sign contracts. full accounting service Paid annually and in a lump sum for the entire term. However, recording the entire value as an expense in a single period would distort the business results between periods. To ensure the matching principle, accounting for accounting service fees should be gradually allocated through prepaid expenses.
Step 1: Record the prepaid expense.
At the time of payment or when an obligation arises for the entire contract period, the value of the service is transferred to account 242:
- Debit Account 242: Service price excluding tax (excluding non-deductible VAT)
- Debit Account 133: Input VAT that is deductible (if any)
- Account 331: Total amount payable (if not yet paid)
- Or, for Account 111, 112: Total amount (if payment is made immediately).
If input VAT is not deductible, this amount is included in the prepaid expense value, increasing the debit side of account 242 accordingly.
Step 2: Allocate periodically to administrative expenses.
At each accounting period (month, quarter, or year), the corresponding value of services used will be transferred from prepaid expenses to administrative expenses:
- Debit Account 642 (Account 6422): The portion of expenses allocated to the period
- Account 242: Value of prepaid expenses allocated.
This approach helps to accurately reflect the actual costs incurred by the business in each period when accounting for accounting service fees, while also ensuring that the business performance report is not "cumulative" at the time of payment.
Important considerations when accounting for accounting service fees.
In addition to basic accounting entries, accountants need to remember several technical points to ensure accurate processing and avoid errors during final settlement:
- Detailed tracking of expense accounts: Account 642 should be detailed according to each expense item. Outsourced accounting services are only one component of management expenses, therefore clearly separating them facilitates easier reconciliation, verification, and explanation later on.
- The nature of Account 242: This prepaid expense account reflects amounts already incurred but related to the operating results of multiple periods. Accurate tracking and allocation of the value in Account 242 is crucial when accounting for accounting service fees for long-term contracts.
- In financial statements: The debit balance of account 133 represents the input VAT that is still deductible and is presented in the current assets section. The debit balance of account 242 will be classified as short-term or long-term prepaid expenses depending on the remaining term of the contract. For entities applying Circular 133, this amount is usually grouped together with the "Other Assets" category.
- Distinguish this from the business of paying taxes on behalf of others. If a service company is authorized by a business to pay taxes on its behalf, the amount paid on their behalf is accounted for separately by the entrusted party through accounts reflecting internal receivables and payables, completely separate from service fees. The business entrusting the service still reflects its own tax obligations through account 333. Confusing these two types of transactions is a common error that leads to inaccurate data.
Conditions for accounting service fees to be deductible when calculating corporate income tax.
One crucial aspect to consider is the validity of the expense when determining taxable corporate income. For service fees to be deductible, businesses must meet three conditions:
- Expenses for business operations
- We have all the necessary legal invoices and documents.
- And if the value is 20 million VND or more, payment must be made using non-cash methods.
It should be noted that if an expense has been correctly recorded according to accounting regulations but does not qualify as a tax-deductible expense, the accountant will not adjust it downward in the books but will only exclude it when preparing the corporate income tax return. This principle helps to clearly separate accounting and tax data, and ensures that the accounting of accounting service fees is always consistent with the original documents.
Conclude
Accounting for accounting service fees is not overly complicated, but it requires accountants to have a thorough understanding of the nature of the expense, clearly distinguish between services incurred in one period or multiple periods, and correctly handle input VAT. By applying the correct accounts according to Circular 200 or Circular 133, and complying with the documentation requirements for tax deductions, businesses will have a transparent accounting system, ready for any tax settlement period. If you still have questions about specific situations, don't hesitate to ask. Contact MAN – Master Accountant Network For the most detailed and accurate answers and support.
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant NetworkHe is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions about Accounting for Accounting Service Fees
Should accounting service fees be recorded in account 642 or account 627? They should be recorded in account 642 (or account 6422 according to Circular 133), because these are general management expenses of the enterprise, not general production expenses.
Instead of recording the entire amount in a single period, record it in account 242 and allocate it gradually over each period to administrative expenses.
Essentially, it's still recorded as an administrative expense, but the input VAT is not separated but included in the expense value.
The expenses are still recorded as administrative costs based on the contract and payment documents. However, to be tax-deductible, the business needs to have a contract, payment documents, and must deduct and declare personal income tax for the service provider as required. If the documentation is insufficient, the expense may be disallowed during tax settlement. Should accounting service fees be recorded in account 642 or account 627?
How should a one-time payment for a full year's services be recorded?
Do businesses that file taxes directly use the same accounting methods?
If I hire an individual to provide accounting services (without issuing invoices), are the accounting entries and expenses valid?






