
The issue of calculating social insurance contributions for foreign workers is a source of confusion for many HR and payroll departments, especially in FDI enterprises employing a large number of foreign experts and managers. Incorrectly determining a salary component, overlooking exchange rate conversion times, or confusing deductible allowances can all lead to underpayment, incorrect payments, and potential retroactive or late payment penalties. This article systematically reviews the legal basis, salary components, foreign currency conversion methods, and common mistakes, helping businesses with foreign workers proactively review their contributions before each payment period.
Why is accurately determining the social insurance contribution salary for foreign workers a pressing issue that cannot be delayed?
Since Social Insurance Law 2024 and Decree 158/2025/ND-CP Effective from July 1, 2025, regulations regarding the eligibility criteria and the salary used as the basis for mandatory social insurance contributions for foreign workers have been clarified. This is a legal basis that all businesses employing foreign workers must understand, as determining the salary for social insurance contributions for foreign workers not only affects the financial obligations of the business but also directly relates to the social security rights of the workers.
Three practical consequences if businesses incorrectly determine the salary used for social insurance contributions for foreign workers:
- Underpayment or incorrect payment resulting in retroactive collection: The Social Insurance agency has the right to require businesses to pay the difference plus late payment interest.
- Direct impact on workers' rights: Lower-than-actual wages used as the basis for contributions mean that the benefits of sick leave, maternity leave, and retirement for foreign workers are reduced.
- Risks during labor inspections: Inconsistencies between payroll records and employment contracts and payrolls are the first thing the inspection team will check.
Therefore, determining the salary for social insurance contributions for foreign workers should be done right from the stage of drafting labor contracts and salary scales, rather than waiting until problems arise.
Legal basis for determining the salary used for social insurance contributions for foreign workers.
Foreign workers are required to participate in mandatory social insurance.
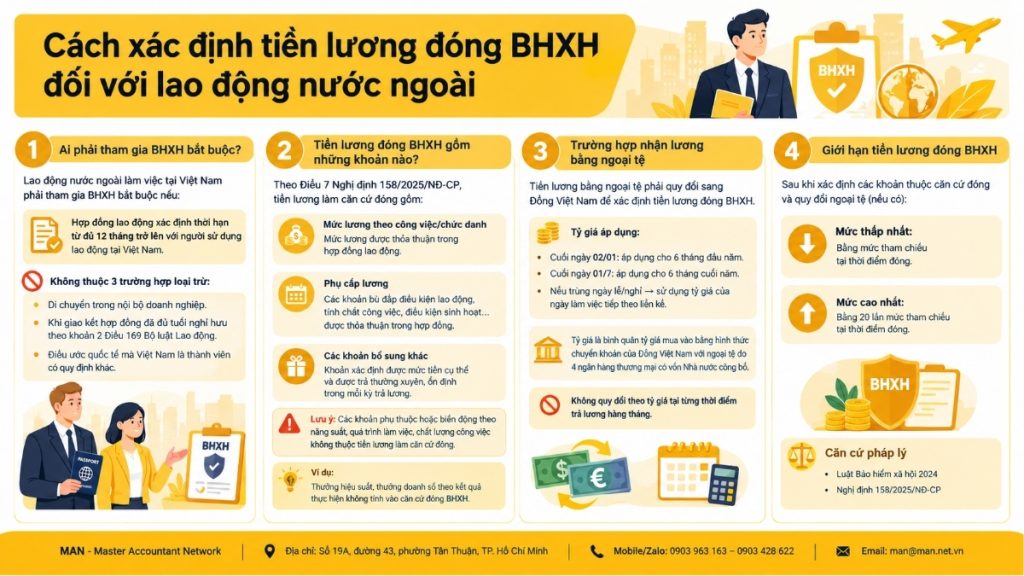
According to Clause 2, Article 2 of the 2024 Social Insurance Law, foreign workers employed in Vietnam are subject to mandatory social insurance when working under a fixed-term employment contract of 12 months or more with an employer in Vietnam.
However, not all foreign workers fall under this category. Three exclusions should be noted when determining the salary for social insurance contributions for foreign workers:
- Internal transfers within a company (typically experts and managers transferred from the parent company overseas).
- The person, at the time of signing the labor contract, had reached the retirement age as stipulated in Clause 2, Article 169 of the 2019 Labor Code.
- In cases where an international treaty to which Vietnam is a party contains different provisions.
Businesses need to review each foreign employee's file according to the three criteria above before concluding whether or not to determine the salary for social insurance contributions for foreign workers.
The salary component used as the basis for social insurance contributions is determined according to Article 7 of Decree 158/2025/ND-CP.
For foreign workers subject to mandatory participation, the salary used as the basis for contributions is determined according to the salary regime decided by the employer, comprising three components as stipulated in Article 7 of Decree 158/2025/ND-CP:
- Salary based on job or position: Calculated based on the time spent on the job or position according to the salary scale or pay table established by the enterprise and agreed upon in the employment contract.
- Salary allowanceCompensation for factors related to working conditions, job complexity, living conditions, and the level of job attractiveness that are not taken into account or are not fully taken into account in the salary, provided that this is agreed upon in the employment contract.
- Other additional charges: The amount of money is specifically determined and paid regularly and consistently in each pay period.
The key point when determining the salary for social insurance contributions for foreign workers is distinguishing between different components. home and which amount not belonging The basis for contribution. Allowances or additional payments are dependent on and fluctuate according to labor productivity, work process, or quality of work performance.
For example: Performance bonuses, monthly sales bonuses, Are not It is included in the salary used as the basis for social insurance contributions.
How to determine the salary for social insurance contributions for foreign workers when receiving salaries in foreign currency.
This is the most specific aspect when determining the salary for social insurance contributions for foreign workers, because the majority of foreign experts and managers are paid in foreign currency according to their contracts.
According to Clause 5, Article 7 of Decree 158/2025/ND-CP, in cases where the salary stated in the labor contract and the salary paid to the employee are in foreign currency, the salary used as the basis for social insurance contributions shall be converted into Vietnamese Dong based on the average buying exchange rate of four state-owned commercial banks via bank transfer.
The timeframe for determining exchange rates is the point most easily overlooked by businesses:
- Exchange rate at end of day January 2nd applicable to first 6 months of the year.
- Exchange rate at end of day July 1st applicable to last 6 months of the year.
- If these two dates coincide with a holiday or day off, the business will use the exchange rate of the next working day.
Therefore, determining the social insurance contribution base salary for foreign workers receiving foreign currency salaries is not based on the exchange rate at the time of monthly salary payment, but is fixed at two points during the year. Businesses need to update these two points correctly to avoid applying the wrong exchange rate throughout half the year.
Salary limits for social insurance contributions for foreign workers.
The salary used as the basis for social insurance contributions for foreign workers, after determining all components and converting to foreign currency (if any), must still comply with the floor and ceiling limits according to the Social Insurance Law 2024:
- Lowest level equal to the reference price at the time of closing.
- highest level equal to 20 times the reference level.
Until the base salary is abolished, the reference level is determined by the base salary as stipulated by current law. This is the final and mandatory step before businesses finalize the amount of salary for social insurance contributions for foreign workers on the declaration form submitted to the social insurance agency.
The 4-step process for determining the social insurance contribution salary for foreign workers.
Here are four steps to help corporate accountants determine the salary for social insurance contributions for foreign workers:
- Step 1 – Identifying the subject: Review the labor contract, contract term, age at the time of signing, and relevant international agreements (if any) to determine whether the foreign worker is subject to mandatory social insurance participation.
- Step 2 – Break down the salary components: Compare the labor contract and salary scale to classify each income item: which is the salary based on job title, which is a fixed allowance, which is a stable supplementary payment, and which is variable based on productivity (not included in the contribution basis).
- Step 3 – Currency conversion (if applicable): Apply the correct exchange rate as of January 2nd or July 1st, based on the average buying rate for transfers from four state-owned commercial banks.
- Step 4 – Compare floor and ceiling and finalize the contribution amount: Compare the results with the minimum and maximum reference levels (20 times the reference level) to finalize the social insurance contribution amount for foreign workers during the period.
Common mistakes when determining the salary for social insurance contributions for foreign workers.
Firstly, performance bonuses and sales bonuses are included in the salary used as the basis for contributions. This is the most common mistake, resulting in the salary used for calculating social insurance contributions for foreign workers being higher than the legally required level.
Second, foreign currency was converted using the exchange rate on payday instead of the fixed exchange rate set at January 2nd and July 1st. This error often persisted for an entire six-month period before being discovered.
Third, omitting excluded groups. Confusing internally transferred employees or employees who have reached retirement age with those required to participate in mandatory social insurance.
Fourth, failure to update the reference level when changes occur. This leads to applying the wrong floor or ceiling when finalizing the salary for social insurance contributions for foreign workers.
Checklist before finalizing payroll for social insurance contributions for foreign workers.
Quick checklist before finalizing payroll for social insurance contributions for foreign workers:
- Confirmation that foreign workers are subject to mandatory social insurance participation according to Clause 2, Article 2 of the Social Insurance Law 2024.
- Exclude cases that are not eligible for participation (internal transfers, reaching retirement age, international treaties).
- Clearly classify salaries, allowances, and supplementary payments according to Article 7 of Decree 158/2025/ND-CP.
- Eliminate productivity and performance-related variables from the closing basis.
- Convert foreign currency at the correct exchange rate and within the applicable timeframe (if salary is paid in foreign currency).
- Compare the floor and ceiling levels to the current reference levels.
Given the volume of detailed review work involved, many FDI companies with foreign personnel have opted for this solution. outsource accounting services We rely on specialized and experienced units like MAN – Master Accountant Network to ensure that the determination of social insurance contributions for foreign workers is always up-to-date and in accordance with the latest regulations, instead of leaving it to internal departments which carries the risk of errors.
Conclude
Determining the salary for social insurance contributions for foreign workers, according to the Social Insurance Law 2024 and Decree 158/2025/ND-CP, revolves around three core points:
- Identify the right target audience.
- Accurately break down the components of the salary.
- And convert using the correct exchange rate when salaries are paid in foreign currency.
Ignoring any of these pillars exposes businesses to the risk of underpayment or incorrect payment, directly impacting the rights of employees.
This task requires regular review of labor contracts, salary scales, and foreign exchange rates at two fixed points each year, rather than a single fixed figure. If your business employs foreign workers and is unsure how to determine the salary for social insurance contributions, the team of experts at MAN – Master Accountant Network is ready to assist. tư vấn to review all payroll records, or implement a complete package through Accounting services for foreign companies To ensure that social insurance obligations for foreign workers are always accurate and up-to-date in accordance with legal regulations.
Contact MAN – Master Accountant Network For free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant NetworkHe is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions about Social Insurance Contribution Calculations for Foreign Workers
Which foreign workers are subject to having their wages determined for mandatory social insurance contributions?
Foreign workers employed under fixed-term employment contracts of 12 months or more with enterprises in Vietnam, except in cases of internal enterprise transfers, having reached retirement age at the time of contract signing, or under international treaties that stipulate otherwise.
Are performance bonuses and sales bonuses included in the salary used for calculating social insurance contributions for foreign workers?
No. Allowances and supplementary payments that fluctuate based on labor productivity, work process, or work quality are not included in the salary used as the basis for contributions.
How is the salary for social insurance contributions calculated for foreign workers who receive their wages in USD?
The conversion is based on the average buying rate via bank transfer of 4 state-owned commercial banks, determined at the end of January 2nd (applicable for the first 6 months of the year) and the end of July 1st (applicable for the last 6 months of the year).
Is there a maximum salary limit for social insurance contributions for foreign workers?
Yes. The highest rate is 20 times the reference rate at the time of closing; the lowest rate is equal to the reference rate.
What responsibilities do businesses have in determining the social insurance contribution base salary for foreign workers?
Employers are responsible for correctly determining the wages used as the basis for contributions, deducting the employee's share of the contribution, and paying it simultaneously into the social insurance fund. They should also regularly review contracts, wage structures, and relevant foreign exchange rates.






