
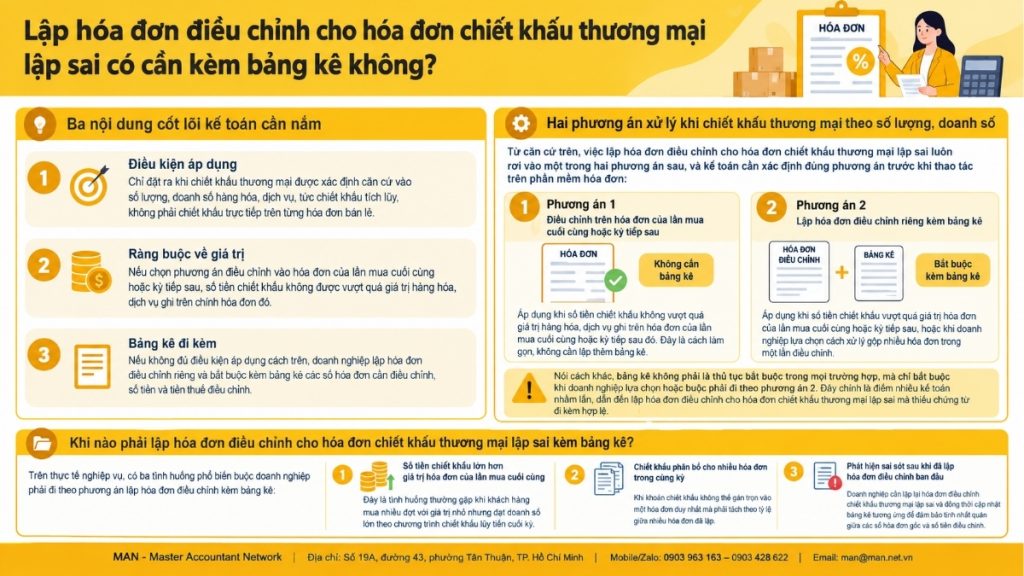
Issuing adjustment invoices for incorrectly issued trade discount invoices is a seemingly familiar procedure, but it is one of the errors most closely scrutinized by tax authorities during tax settlement. Simply missing the accompanying statement or making an incorrect invoice adjustment can result in the entire legitimate discount amount being disallowed from revenue and expenses. This article summarizes the legal basis for this process. Decree 254/2026/ND-CPThese two legally permitted processing options, along with the mandatory statement content and implementation procedures, help accountants process invoices correctly from the very first one.
Why is creating an adjustment invoice for an incorrectly issued trade discount invoice always a concern for accountants?
Quantity-based or sales-based trade discounts are a common sales policy, but their representation on electronic invoices is not as simple as discounts applied directly to each sale. When the discount is only determined after multiple purchases or at the end of the period, accountants are forced to go back and adjust previously issued invoices, and this is where the need arises to create adjustment invoices for incorrectly issued trade discount invoices.
The problem lies in the fact that many businesses only issue adjustment invoices to reduce the value, forgetting the required accompanying documents, or making incorrect adjustments to ineligible invoices. The consequences are not only invalid invoices but also risks related to output and input value-added tax, and deductible expenses when calculating corporate income tax.
Therefore, issuing an adjustment invoice for an incorrectly issued trade discount invoice is not just a technical operation on the electronic invoicing software, but a process that must strictly adhere to current legal regulations to avoid being reassessed during tax audits and inspections.
Legal basis for issuing adjustment invoices
The original regulation governing this matter is found in point b, clause 5, Article 10 of Decree 254/2026/ND-CP on handling issued electronic invoices. This is the only and direct legal basis that accountants need to adhere to when preparing adjustment invoices for incorrectly issued trade discount invoices.
What does Point b, Clause 5, Article 10 of Decree 254/2026/ND-CP stipulate?
Based on Point b, Clause 5, Article 10 of Decree 254/2026/ND-CP:
In cases where trade discounts are based on the quantity or sales volume of goods or services, the discount amount for goods or services sold shall be adjusted on the sales invoice of the last purchase or the subsequent period, ensuring that the discount amount does not exceed the value of goods or services recorded on the invoice of the last purchase or the subsequent period. Alternatively, an adjustment invoice shall be issued accompanied by a list of the invoices requiring adjustment, the adjusted amount, and the adjusted tax.
Three key accounting points to understand when preparing adjustment invoices for incorrectly issued trade discount invoices:
- Terms and conditions apply: This only applies when the trade discount is determined based on... quantity, sales This refers to cumulative discounts on goods and services, not direct discounts on individual retail invoices.
- Value constraints: If you choose to have the discount adjusted to the invoice of the last purchase or the next period, the discount amount will be applied. must not exceed The value of goods and services recorded on that invoice.
- The following is a list of items to be included: If the above method is not applicable, the business must issue a separate adjustment invoice and A list of items is required. The invoice numbers that need adjustment, the adjusted amounts, and the adjusted tax amounts.
Two options for handling quantity-based and sales-based trade discounts.
Based on the above, creating an adjustment invoice for an incorrectly issued trade discount invoice always falls into one of two options, and accountants need to determine the correct option before making any changes in the invoicing software:
- Option 1 – Adjustment on the invoice for the last purchase or the next period: This applies when the discount amount does not exceed the value of goods or services recorded on the invoice of the last purchase or the subsequent period. This is a simplified method that does not require creating an additional list.
- Option 2 – Issue a separate adjustment invoice with a detailed list: This applies when the discount amount exceeds the invoice value of the last purchase or the subsequent period, or when the business chooses to consolidate multiple invoices into a single adjustment.
In other words, the statement is not a mandatory procedure in all cases, but only when the business chooses or is forced to follow option 2. This is where many accountants misunderstand, leading to the creation of adjustment invoices for incorrectly issued trade discount invoices lacking valid supporting documents.
When is it necessary to issue an adjustment invoice for an incorrectly issued trade discount invoice, along with a detailed list of discounts?
In practice, there are three common situations that require businesses to issue adjustment invoices accompanied by a detailed list:
- The discount amount is greater than the invoice value of the last purchase: This is a common situation when customers make multiple purchases of small value but achieve high sales volume due to a cumulative discount program at the end of the period.
- Discounts are allocated across multiple invoices within the same period: When the discount cannot be applied entirely to a single invoice but must be split proportionally across multiple invoices.
- Errors discovered after the initial adjustment invoice had been issued: Businesses need to reissue the invoice adjusting the incorrectly issued trade discount and simultaneously update the corresponding statement to ensure consistency between the original invoice numbers and the adjusted amount.
In all three situations above, omitting the statement does not immediately invalidate the adjusted invoice in the system, but it will leave the business without a basis to prove the reasonableness and validity of the discount amount when the tax authorities request verification. The consequence is the risk of the expense being disallowed and the deductible value-added tax being reduced.
What is the currently used template for a commercial discount invoice?
Currently, there are no specific legal regulations governing the template for the commercial discount invoice statement.
However, in practice, the Commercial Discount Invoice Statement Template is used to detail original invoices that receive discounts when a business reduces the price of goods sold (usually at the end of the period or after multiple purchases). Therefore, this document is attached to adjustment invoices or discount invoices to prove the legality of expenses, revenue, and adjustments to output or input value-added tax.
Therefore, you can refer to the sample invoice statement for trade discounts below:
What information should be included in a trade discount invoice statement?
According to the wording in point b, clause 5, Article 10 of Decree 254/2026/ND-CP, the list used for preparing adjustment invoices for incorrectly issued trade discount invoices must include at least three contents:
- The invoice numbers need adjustment.List the full symbols, invoice numbers, and issuance dates of each original invoice that falls within the discount range.
- Adjustment amountThe discount value is allocated accordingly to each invoice in the list.
- Tax adjustments (if any)The value-added tax portion changes according to the discount amount of each invoice.
An important storage principle: this statement is stored at the unit and only needs to be presented when requested by the tax authorities or competent state agencies, and is not required to be submitted along with electronic invoices to the tax authority's system at the time of issuance. This means that businesses must organize the storage of the statement in a systematic way, so that it can be retrieved immediately when needed, instead of creating it haphazardly and then losing it.
Procedure for issuing adjustment invoices for incorrectly issued trade discount invoices, including a detailed list.
To minimize errors, accountants should create adjustment invoices for incorrectly issued trade discount invoices following this procedure:
- Step 1 – Determine the basis for the discount: Compare the sales policy, contract, or discount notice to confirm that the discount is calculated based on quantity or sales volume, not a direct discount on each invoice.
- Step 2 – Determine the solution: Compare the discount amount with the invoice value of the last purchase or the next period to choose one of the two options mentioned in point b, clause 5, Article 10.
- Step 3 – Prepare a summary (if option 2 applies): List all invoices requiring adjustment, the corresponding adjusted amount, and the adjusted tax for each invoice.
- Step 4 – Create an adjustment invoice for the incorrectly issued trade discount invoice: Issue the adjustment invoice on the electronic invoicing system, clearly stating the reduction adjustment and referencing the attached statement.
- Step 5 – Record keeping: Keep the statement along with the adjustment invoice, contract, and discount policy at the unit, ready to present when the tax authorities request verification.
- Step 6 – Reconcile tax declarations: Update the adjusted figures in the value-added tax return for the period in which the adjusted invoice was issued, ensuring consistency between the invoice, the statement, and the declared figures.
Common mistakes when preparing adjustment invoices for incorrectly issued trade discount invoices.
Firstly, confusing sales-based trade discounts with payment discounts is a common mistake. These two types of discounts have different natures and invoice processing methods; applying the wrong legal basis leads to the creation of adjustment invoices for incorrectly issued trade discount invoices right from the initial planning stage.
Secondly, adjusting the invoice beyond the value of the last purchase without including a separate statement of transactions is a direct violation of the conditions in point b, clause 5, Article 10 of Decree 254/2026/ND-CP, rendering the adjusted invoice legally invalid.
Third, the statement lacked mandatory information. The statement only recorded the invoice number and discount amount but omitted the corresponding tax adjustment amount, resulting in discrepancies when reconciling output value-added tax.
Fourth, the summary sheet is not systematically stored. Because the summary sheet does not need to be submitted to the tax authorities immediately, many businesses are negligent in storing it completely, and when requested to present it, it can no longer be compared with the original invoices.
Fifth, the adjusted figures were not updated in the corresponding declaration period. Incorrectly prepared invoices for trade discounts were correctly issued, but the figures on the value-added tax return did not reflect the adjustment in a timely manner, creating a discrepancy between the accounting records and the tax declaration documents.
Managing invoices and supporting documents within the overall tax management system: Why businesses need to pay attention.
According to Article 5 of the 2025 Law on Tax AdministrationInvoice and document management is one of the official aspects of tax administration, alongside tax declaration, tax calculation, and tax audit. This shows that issuing adjustment invoices for incorrectly issued trade discount invoices is not a standalone accounting operation, but falls within the direct supervision of the tax authorities through invoice and document management and tax audits.
For businesses with a high frequency of trade discounts, especially distribution and wholesale businesses with progressive discount policies based on sales volume, establishing a standardized process for creating adjustment invoices for incorrectly issued trade discount invoices, along with a detailed list from the outset, will significantly reduce the workload of year-end review and minimize the risk of being assessed for tax during audits.
If the internal accounting department lacks experience in handling complex invoice adjustment situations, the business may consider using a professional service. full accounting service We utilize specialized, experienced units like MAN – Master Accountant Network to ensure that all invoices, statements, and tax returns are processed consistently and correctly from the outset.
Checklist of actions to take when creating an adjustment invoice for an incorrectly issued trade discount invoice.
Before issuing an adjustment invoice, the accountant should quickly check the following five items:
- The correct discount is a quantity-based trade discount, as defined in point b, clause 5, Article 10 of Decree 254/2026/ND-CP.
- Compare the discount amount with the invoice value of your last purchase or the next purchase to choose the correct solution.
- Prepare a complete list of invoice numbers, amounts, and adjusted tax amounts (if applicable under a separate adjustment invoice scheme).
- Keep the statements on file at the unit, ready to present when requested by the tax authorities.
- Update the adjusted figures in the value-added tax return for the correct period in which the transaction occurred.
Conclude
The answer to the question "Is it necessary to include a list of items when issuing an adjustment invoice for an incorrectly issued trade discount invoice?" depends on whether the discount amount exceeds the invoice value of the last purchase or the subsequent period. If it does not exceed the limit, the business can adjust the invoice directly without a list of items; if it exceeds the limit or chooses to issue a separate adjustment invoice, a list of items is a mandatory document to include, in accordance with point b, clause 5, Article 10 of Decree 254/2026/ND-CP.
Since there is currently no official form issued by the government, businesses need to create their own form ensuring it includes all three necessary elements:
- The invoice number needs adjustment;
- Adjusted amount;
- And the tax amounts are adjusted and stored systematically for reference when needed.
If your business is still unsure about how to create adjustment invoices for incorrectly issued trade discount invoices in specific situations, or needs to review its entire current discount policy, MAN's team of experts is ready to assist through our service. accounting consulting servicesThis helps businesses process invoices correctly from the very first invoice, instead of waiting until they are asked for clarification by the tax authorities. For businesses that want to optimize internal resources, this solution... outsource accounting services It is also a worthwhile option to consider to ensure that all invoicing and documentation operations are carried out continuously and in accordance with regulations.
Contact MAN – Master Accountant Network For free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant NetworkHe is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions about Invoice Adjustment for Incorrectly Issued Trade Discount Invoices
Is it mandatory to include a list of items on the invoice when issuing an adjustment for an incorrectly issued trade discount invoice?
Not in all cases. If the discount amount does not exceed the value of goods or services recorded on the invoice of the last purchase or the subsequent period, the business can adjust directly on that invoice without a separate statement. A separate statement is only required when creating a separate adjustment invoice according to point b, clause 5, Article 10 of Decree 254/2026/ND-CP.
What information should a trade discount invoice statement include?
At least three details are required: the invoice numbers needing adjustment, the adjustment amount, and the adjustment tax amount (if any).
Does the statement need to be submitted to the tax authorities immediately when issuing an adjusted invoice?
No. The statement is kept at the unit and is only presented when requested by the tax authorities or other competent state agencies.
Is there an official template for a trade discount invoice yet?
No. Current legislation does not specify a particular template; businesses can design their own templates as long as they ensure they include all the required information.
What happens if the discount amount exceeds the invoice value of the last purchase?
Businesses are not allowed to make direct adjustments to the original invoice; instead, they must issue a separate adjustment invoice accompanied by a list of the invoices requiring adjustment, the adjusted amounts, and the corresponding adjusted tax amounts.






