
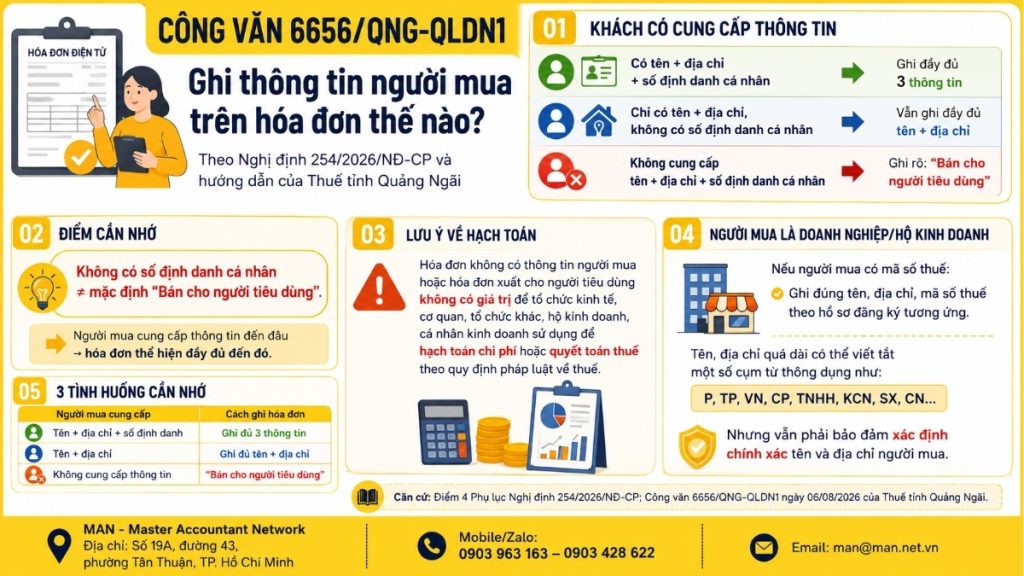
Official document 6656/QNG-QLDN1 of 2026 from the Quang Ngai Provincial Tax Department provides direct guidance on a common problem faced by almost all retail accountants: how should an invoice be correctly filled out if the buyer only provides their name and address, without a personal identification number? This seemingly minor detail is crucial to the legal validity of the invoice and the buyer's right to account for expenses. The following article summarizes the original regulation in Section 4 of the Appendix. Decree 254/2026/ND-CPThe document includes guidance content, three real-life scenarios, and common mistakes.
How should Official Document 6656/QNG-QLDN1 be implemented?
Official document 6656/QNG-QLDN1 is a document from the Quang Ngai Provincial Tax Department, providing guidance on how to record buyer information on invoices in cases where the buyer does not have a personal identification number, based on the regulations in Section 4 of the Appendix issued with Decree 254/2026/ND-CP.
- Firstly, the frequency of occurrence is extremely high: Retail businesses, restaurants, hotels, transportation companies, and digital services issue thousands of invoices to individual customers every month. A single misinterpretation of a rule can lead to widespread errors, not just one incorrect document.
- Secondly, the invoicing software requires you to select one of the following options: The "personal identification number" field is a new addition to the invoice data structure. When customers do not provide it, staff must make an immediate decision at the counter: leave it blank, write the name and address, or write "Sold to Consumer". Circular 6656/QNG-QLDN1 serves as the basis for standardizing this selection.
- Thirdly, the consequences fall on the buyer: An invoice lacking buyer information is not just a formality; it can prevent the expense from being used for accounting purposes or tax settlement. The risk therefore extends to your business customers.
Legal basis: Section 4 of the Appendix to Decree 254/2026/ND-CP and the content of Official Letter 6656/QNG-QLDN1
Based on Section 4 of the Appendix issued with Decree 254/2026/ND-CP, the information of the buyer on the invoice is recorded as follows:
If the buyer is a business entity (economic organization, household business, individual business) with a tax identification number, the name, address, and tax identification number of the buyer shown on the invoice must be exactly as stated in the business registration certificate, branch registration certificate, household business registration certificate, tax registration certificate, tax identification number notification, investment registration certificate, or cooperative registration certificate; if the buyer provides a budget-related unit code, the name, address, and budget-related unit code shown on the invoice must be the assigned budget-related unit code.
The original regulation is in point b, section 4: The buyer is the consumer.
If the buyer is a consumer who provides their name, address, and personal identification number, the invoice must show their name, address, and personal identification number (for foreign buyers providing information for invoice creation, the address and personal identification number may be replaced by their passport number or entry/exit document and nationality); if the buyer does not provide their name, address, and personal identification number, the invoice must clearly state "Sold to consumer". In some specific cases of selling goods or providing services to individual consumers as stipulated in point 9 of this Appendix, the invoice does not need to show the name, address, and personal identification number of the buyer.
Important Note: Invoices without buyer information or invoices issued to consumers are invalid for use by economic organizations, agencies, other organizations, business households, and individual businesses for the purpose of accounting for expenses or settling taxes according to tax laws.
See more: Invoices must be issued in accordance with Decree 254/2026/ND-CP.
The instructions are contained in Official Letter 6656/QNG-QLDN1.
If the buyer is a consumer who provides their name, address, and personal identification number, or only their name and address but no personal identification information, the invoice must reflect the full information provided by the buyer; if the buyer does not provide their name, address, and personal identification number, the invoice must clearly state "Sold to consumer".
The invoice reflects only the information provided by the buyer. The lack of a personal identification number does not deprive the seller of the right to record the customer's name and address, nor does it allow the seller to automatically switch to recording "Sold to Consumer".
Three scenarios for recording buyer information according to Official Letter 6656/QNG-QLDN1
The entire guidance in Official Letter 6656/QNG-QLDN1 can be summarized into three situations:
| Situation | Buyer information | How it's presented on the invoice |
| 1 | Name, address, and personal identification number | Show all three pieces of information |
| 2 | Only name and address, no personal identification information. | The information provided by the buyer (name, address) must be fully and accurately reflected. |
| 3 | Do not provide name, address, or personal identification number. | Please specify. "Sell to consumers" |
For foreign buyers, the regulations allow for the replacement of address and personal identification number with the customer's passport number or entry/exit document and nationality.
Furthermore, in certain cases of selling goods or providing specific services to individual consumers as stipulated in point 9 of the Appendix, the invoice does not need to show the name, address, or personal identification number of the buyer. This is an exceptional group that requires separate verification and should not be interpreted in broad terms.
For businesses with multiple sales outlets and frequent staff turnover, standardizing the three scenarios above into internal procedures is often assigned to the accounting department or the supplier. full accounting service To ensure all counters handle everything the same way.
Rules for abbreviating buyer's name and address.
This is supplementary information that is often overlooked when reading Official Letter 6656/QNG-QLDN1 and the original regulations. If the buyer's name and address are too long, the seller may use a shortened version of some common nouns:
| Complete set | Abbreviations are permitted. |
| Ward | P |
| City | City |
| Vietnam | Vietnam |
| Share | CP |
| Limited liability | Ltd. |
| Industrial zone | industrial park |
| Manufacture | SX |
| Branch | CN |
The binding conditions require that the information include the full house number, street name, ward, commune, special zone, province, and city, accurately identifying the business name and address, and matching the business registration and tax registration information.
In other words, abbreviations are a right to shorten common nouns, not a right to omit place names. An address that omits the ward/commune name or house number, even if concise, is still unacceptable.
The most serious consequence: Invoices without buyer information cannot be used to record expenses.
Invoices without buyer information or invoices issued to consumers are invalid for use by economic organizations, agencies, other organizations, business households, and individual businesses for the purpose of accounting for expenses or settling taxes.
Three real-world scenarios arising from the regulation:
- If an employee goes on a business trip to purchase goods and forgets to issue an invoice with the company's tax identification number: The invoice marked "Sold to Consumer" will not be usable for expense accounting purposes when brought back to the accounting department.
- Business customers provide business cards instead of registration documents: The trade abbreviation does not match the business registration certificate, leading to the risk of expense disallowance on the buyer's side.
- When selling online, the system automatically fills in "Sold to Consumer" by default: If the customer is a business but the invoice doesn't contain buyer information, adjustments and replacements must be processed, which is both time-consuming and creates an anomaly in the invoice data.
Conclude
Three most memorable points from Official Letter 6656/QNG-QLDN1 and Section 4 of the Appendix to Decree 254/2026/ND-CP:
- The invoice must fully reflect the information provided by the buyer.
- The phrase "Sold to consumers" is only used when the customer does not provide their name, address, or personal identification number;
- Invoices without buyer information are invalid for accounting purposes or tax settlement.
If your company's invoicing process has any uncertainties, MAN – Master Accountant Network's team of tax and invoicing experts is ready to review it with your company before mass issuance. An independent review is always less burdensome than a large-scale adjustment or replacement of invoices.
Contact MAN – Master Accountant Network For free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant NetworkHe is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions about Official Document 6656/QNG-QLDN1
If the customer only provides their name and address, without a personal identification number, how should the invoice be filled out?
According to Official Letter 6656/QNG-QLDN1, invoices must fully reflect the information provided by the buyer, i.e., the customer's name and address, and should not be changed to "Sold to Consumer".
When is it labeled "For sale to consumers"?
When the buyer does not provide their name, address, or personal identification number, the invoice will clearly state "Sold to consumer".
Can an invoice marked "Sold to Consumer" be used for accounting purposes?
No. Invoices without buyer information or invoices issued to consumers are not valid for use by economic organizations, agencies, other organizations, business households, or individual businesses for the purpose of accounting for expenses or settling taxes according to tax laws.
How should the buyer's information be recorded if they are a foreigner?
Address information and personal identification numbers may be replaced with the customer's passport number or immigration document and nationality.
If the buyer is a business, where do they get the information to issue the invoice?
Record according to the business registration certificate, branch registration certificate, household business registration certificate, tax registration certificate, tax code notification, investment registration certificate, or cooperative registration certificate; if the buyer provides a budget-related unit code, show the issued budget-related unit code.






