
The exchange rate used to record inventory purchased in foreign currency is a key issue that causes many accountants in import-export businesses to revise their accounting entries immediately upon application. Circular 99/2025/TT-BTCSimply using the wrong exchange rate for calculating taxes on the customs declaration to record the value of goods entering the warehouse, or forgetting to separate the foreign currency advance paid to the seller, can cause the cost of inventory to be inaccurate, leading to discrepancies in cost of goods sold, profit, and corporate income tax settlement figures. This article systematically reviews the correct wording of the document, three application scenarios, and the most common errors corrected by auditors.
Why is the exchange rate used to record inventory purchased in foreign currency a problem for the 2026 accounting period?
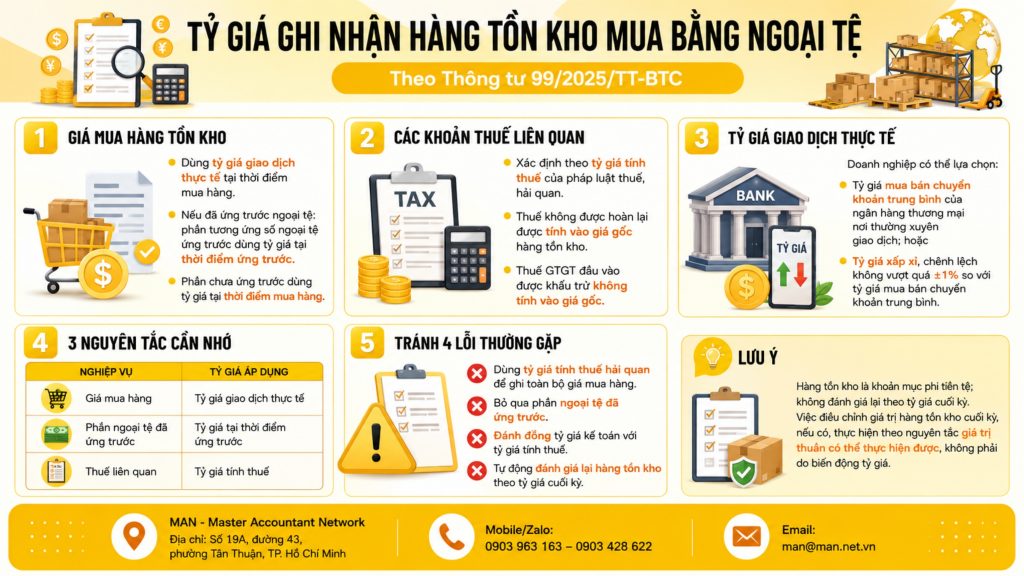
According to Circular 99/2025/TT-BTC, the exchange rate used to record inventory purchased in foreign currency is the actual transaction rate at the time of purchase. For the purchase price portion, the actual transaction rate at the time of the advance payment is applied; related taxes are determined according to the tax exchange rates stipulated by tax and customs laws.
Three different exchange rates, at three different times, all included in the same shipment. That's why this operation is more prone to errors than people realize.
Circular 99/2025/TT-BTC replaces Circular 200 from January 1, 2026.
Circular 99/2025/TT-BTC, issued by the Ministry of Finance on October 27, 2025, provides guidance on the accounting regime for enterprises. It takes effect from January 1, 2026, and applies to fiscal years beginning on or after January 1, 2026, replacing Circular 200/2014/TT-BTC and its amending and supplementing circulars.
For businesses involved in import activities, the directly affected aspects are the inventory accounting principles in Appendix II and the exchange rate application principles in Account 413, two elements that entirely determine how to record the exchange rate for inventory purchased in foreign currency.
Three risks of incorrectly determining the exchange rate for recording inventory purchased in foreign currency according to Circular 99:
- Incorrect inventory cost: If the inventory value is incorrect, the average unit price will be incorrect, the cost of goods sold will be incorrect, and this error will spread to all remaining inventory periods.
- Exchange rate discrepancy: The difference that should have been reflected in Account 413 was hidden in the value of materials, obscuring the foreign currency transaction from the records.
- Risks during tax settlement: A downward adjustment in cost of goods sold means an increase in taxable income, along with late payment penalties calculated backward in the period in which the transaction occurred.
Legal basis for determining the exchange rate for recording inventory purchased in foreign currency.
As stipulated in Clause 10 of the principles of inventory accounting, Appendix II issued with Circular 99/2025/TT-BTC:
For inventory purchased in foreign currency, the purchase price must be based on the actual exchange rate at the time of purchase to record the value of the inventory received (except in cases where an advance payment is made to the seller, in which case the value of the inventory corresponding to the amount of foreign currency advanced is recorded at the actual exchange rate at the time of the advance). Taxes related to inventory purchased in foreign currency are determined according to the tax exchange rate stipulated by tax and customs laws. Accounting for inventory purchases in foreign currency is carried out according to the guidelines in Account 413 – Exchange Rate Differences.
This principle is consistent with the principle of cost at Clause 1, Article 6 of the Accounting Law 2015 This is the value of the asset initially recorded at its original cost, i.e., the value at the time the transaction occurs, without adjusting for subsequent exchange rate fluctuations.
The actual exchange rate, the core of the exchange rate used to record inventory purchased in foreign currency.
According to the guidelines in Account 413 – Exchange Rate Differences, enterprises may choose the actual exchange rate on the transaction date as the average buying and selling rate of the commercial bank where the enterprise regularly conducts transactions, or an approximate rate with a difference not exceeding +/- 1% compared to the aforementioned average buying and selling rate.
Here are two specific points to note:
- The exchange rate selection must be consistent and explained in the Notes to the Financial Statements. It is not permissible to use the average exchange rate in one period and an approximate exchange rate in the next.
- If commercial banks that regularly conduct transactions do not publish the exchange rate of the foreign currency involved, businesses may choose an intermediate currency for conversion, but must apply it consistently and explain the basis for the choice.
Reference: Exchange rates for export invoices according to Circular 99.
Distinguish between actual transaction exchange rates and book exchange rates.
When purchasing inventory using foreign currency, two exchange rates appear in the same accounting entry but serve two different purposes:
| Regarding accounting entries | Applicable exchange rate |
| Debit side of inventory accounts (152, 153, 156…) | The actual exchange rate at the time of purchase. |
| The creditor has a cash account (111, 112) when making payments. | Book exchange rate (specific or weighted average) |
| Debit side of accounts payable to suppliers when making advance payments. | The actual exchange rate at the time of advance payment. |
The difference between the two sides is handled according to the guidelines in Account 413 – Exchange Rate Differences. Exchange rate differences must not be added to the cost of inventory; this is a principle that must be strictly adhered to.
3 scenarios for applying exchange rates to record inventory purchased in foreign currency.
Situation 1: Buying goods without paying the seller in advance.
The entire purchase price is converted according to the actual exchange rate at the time of purchase, i.e., the time of transfer of ownership according to the delivery terms of the contract, as shown on the warehouse receipt and import documents.
Subsequent payment to the seller does not change the value of the goods already in inventory. If the exchange rate on the payment date is higher than the exchange rate recorded for the debt, the difference is an exchange rate loss, not a purchase cost.
Situation 2: An advance payment is made to the seller.
This is the exception stated in parentheses in clause 10. The inventory value is then composed of two parts:
- The corresponding amount of foreign currency advanced: Converted according to the actual exchange rate at the time of advance payment, remaining unchanged regardless of fluctuations in the exchange rate on the day of delivery.
- Remaining balance: Converted according to the actual exchange rate at the time of purchase.
This principle aligns with the accounting principle for liabilities: when a prepayment is made, the debit side of the liabilities account applies the actual exchange rate at the time of prepayment; upon receipt of goods, the credit side of the liabilities account corresponding to the prepaid foreign currency also applies the exchange rate at the time of prepayment.
Situation 3: Import taxes
Import duties, excise taxes, and environmental protection taxes that are non-refundable are included in the cost of inventory, but the tax amount is determined according to the tax exchange rate stipulated by tax and customs laws, not the accounting exchange rate currently used by the enterprise.
Practical consequences: In the same import declaration, the purchase price and the tax portion can be converted using two different exchange rates. This is a point where novice accountants can easily "force" the entire shipment to use a single exchange rate to simplify the accounting records, and it's also the first point of review during an audit.
Value-added tax on imported goods that is eligible for deduction is not included in the cost of inventory.
This example illustrates how to determine the exchange rate for recording inventory purchased in foreign currency.
Company B imported a batch of raw materials worth USD 100,000, with an import tax rate of 5%, and the import VAT is deductible.
| Milestones in professional record | Data |
| March 15, 2026: Advance payment to the seller. | 30,000 USD, actual exchange rate 25,800 VND/USD |
| April 10, 2026: Goods received and stored in the warehouse. | The actual exchange rate is 26,000 VND/USD. |
| April 10, 2026: Customs declaration form | The exchange rate for tax purposes is 25,900 VND/USD. |
The calculation steps are as follows:
- Amount already paid in advance: 30,000 × 25,800 = 774,000,000 VND;
- The remaining amount: 70,000 × 26,000 = 1,820,000,000 VND;
- Recorded purchase price = 774,000,000 + 1,820,000,000 = 2,594,000,000 VND;
- Taxable import value = 100,000 × 25,900 = 2,590,000,000 VND, resulting in import tax = 5% × 2,590,000,000 = 129,500,000 VND
- Cost of inventory received = 2,594,000,000 + 129,500,000 = 2,723,500,000 VND.
If the accountant uses a single exchange rate of 26,000 for the entire shipment, the purchase price would be 2,600,000,000 VND, which is 6 million VND higher than the correct amount. Furthermore, the exchange rate difference, which should have been accounted for separately, has been included in the cost of materials.
Summary of journal entries:
- When making an advance payment: Debit Account 331 (774,000,000) / Credit Account 112 at the book exchange rate, the difference is handled according to Account 413.
- Upon receiving the goods into inventory: Debit Account 152 (2,594,000,000) / Credit Account 331 (2,594,000,000).
- Import tax: Debit Account 152 (129,500,000) / Credit Account 3333 (129,500,000).
After inventory is received: Inventory is not revalued at the end-of-period exchange rate.
One principle that needs to be clearly stated to avoid distorting correctly recorded data is that inventory is a non-monetary item. At the end of the accounting period, businesses only revalue monetary items denominated in foreign currency (cash, receivables, payables in foreign currency) at the average buying and selling exchange rate of the commercial bank with which they regularly conduct transactions.
The value of the goods received into inventory remains unchanged at the exchange rate used to record inventory purchased in foreign currency at the time of initial recording, regardless of whether the year-end exchange rate increases or decreases.
If the net realizable value is lower than the original cost due to damage, obsolescence, or a decrease in selling price, the enterprise shall create a provision for inventory devaluation as guided in Account 229 (Provision for asset impairment). This is an adjustment based on net value, not an adjustment based on exchange rate.
Please note the following: Advance payments made to suppliers for the purchase of goods are non-monetary in nature because the portion that will be received in kind is non-monetary, and therefore are not subject to revaluation at the end of the period like regular accounts payable.
5 common mistakes when determining the exchange rate for recording inventory purchased in foreign currency.
Here are five common mistakes when determining the exchange rate for inventory purchased in foreign currency:
- Use the exchange rate on the customs declaration form to record the value of goods entering the warehouse: The exchange rate only applies to the tax portion; the purchase price portion must be based on the actual transaction exchange rate.
- Ignoring the advance payment in foreign currency: The entire shipment was converted using the exchange rate on the day of receipt, resulting in errors in both the original price and the outstanding foreign currency balance.
- Adding exchange rate differences to the cost of inventory: Differences arising from payments are treated under Account 413, and are not a component of the purchase price.
- Revaluation of inventory at the end-of-period exchange rate: Misrepresents the nature of non-monetary items and inflates or distorts the cost of goods sold in the following period.
- Inconsistency in exchange rate selection: Businesses use approximate exchange rates but do not control the spread threshold of +/-1%, or change reference banks mid-term without explanation.
For businesses with high import frequency, standardizing the process of obtaining daily exchange rates and maintaining records of those rates should be included in internal accounting regulations from the beginning of the fiscal year; if the internal accounting department lacks sufficient personnel, consider consulting with others. full accounting service Seek assistance from specialized and experienced units such as MAN – Master Accountant Network.
Conclude
Three things to remember about the exchange rate for recording inventory purchased in foreign currency according to Circular 99/2025/TT-BTC:
- The purchase price is based on the actual exchange rate at the time of purchase;
- The amount paid in advance is based on the exchange rate at the time of payment;
- The tax portion is calculated according to the exchange rate stipulated by tax and customs laws.
Beyond those three points, any subsequent exchange rate fluctuations are exchange rate differences, not the original price.
2026 is the first year of the new accounting system's implementation, and also the year when comparative figures and conversion balances are most prone to discrepancies. Importing businesses should review their exchange rate policies during the period, rather than waiting for auditors to point them out.
If your accounting department is unsure about how to apply the exchange rate for recording foreign currency-denominated inventory purchases for shipments with advance payments or multiple import taxes, the expert team at MAN – Master Accountant Network is ready to provide support. accounting consultingFor businesses looking to optimize their operational costs, this option is... outsource accounting services Standardizing the recording of inventory purchased in foreign currency usually yields noticeable results from the very first period.
Contact MAN – Master Accountant Network For free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant NetworkHe is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions Regarding Exchange Rates for Recording Inventory Purchased in Foreign Currency
Is the exchange rate used to record inventory purchased in foreign currency the bank's buying rate or selling rate?
This is the actual exchange rate at the time of purchase, determined by the average buying and selling rate of the commercial bank where the business regularly conducts transactions, or an approximate rate with a difference of no more than +/- 1% compared to this rate.
If I've already paid 100% in advance for the goods, which exchange rate should I use?
The entire value of inventory corresponding to the foreign currency advance is recorded at the actual exchange rate at the time of the advance, not the exchange rate on the day the goods are received.
Is it permissible to use the exchange rate on the customs declaration form to record the value of goods entering the warehouse?
No. The exchange rate used for tax calculation according to tax and customs laws is only used to determine related taxes. The purchase price must still be based on the actual exchange rate.
Are exchange rate differences when paying suppliers included in the inventory value?
No. This difference is handled according to the guidelines in Account 413 – Exchange Rate Differences, and does not change the original cost of goods already in inventory.
Is it necessary to re-evaluate inventory at the end of the year using current exchange rates?
No. Inventory is a non-monetary item. At the end of the period, only monetary items denominated in foreign currency are revalued; if inventory depreciates in value, a provision is made according to Account 229.






