
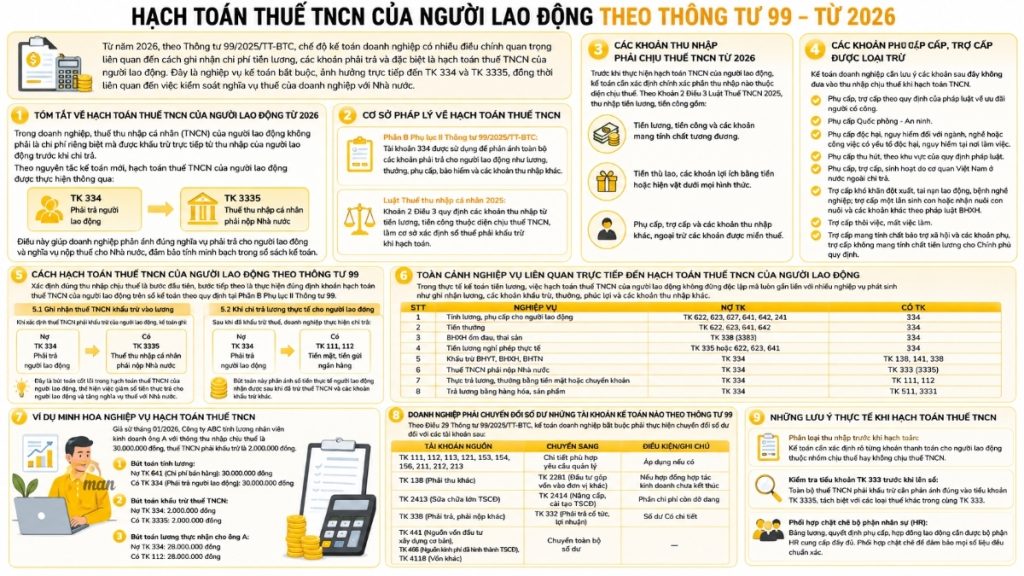
From 2026, according to Circular 99/2025/TT-BTCThe corporate accounting system has undergone several important adjustments related to the recording of salary expenses, payables, and especially the accounting of personal income tax for employees. This is a mandatory accounting operation, directly affecting accounts 334 and 3335, and is also related to controlling the enterprise's tax obligations to the State.
Summary of personal income tax accounting for employees in businesses from 2026
In businesses, personal income tax (PIT) for employees is not a separate expense but is deducted directly from the employee's income before payment.
According to the new accounting principles, the personal income tax of employees is accounted for through:
- Account 334 – Payable to employees
- Account 3335 – Personal income tax payable to the State.
This helps businesses accurately reflect their obligations to pay employees and their tax obligations to the State, ensuring transparency in their accounting records.
Legal basis for accounting for personal income tax of employees according to Circular 99.
To properly perform the accounting of personal income tax for employees, accountants need to base their work on the following two main legal documents:
- Part B, Appendix II of Circular 99/2025/TT-BTC: Account 334 is used to reflect all amounts payable to employees such as salaries, bonuses, allowances, insurance, and other income.
- Personal Income Tax Law 2025Clause 2 of Article 3 stipulates that income from salaries and wages is subject to personal income tax, serving as the basis for determining the amount of tax to be withheld when accounting for income.
Income that is excluded and income subject to personal income tax from 2026.
Before accounting for an employee's personal income tax, the accountant must accurately determine which income is subject to tax. According to Clause 2, Article 3 of the Personal Income Tax Law 2025, salary and wage income includes:
- Salaries, wages, and equivalent payments.
- Remuneration, monetary or in-kind benefits in any form.
- Allowances, subsidies, and other income, excluding those that are tax-exempt.
Allowances and subsidies are excluded.
Business accountants should note that the following items are not included in taxable income when accounting for employee personal income tax:
- Allowances and subsidies as prescribed by law regarding preferential treatment for meritorious individuals.
- Defense and Security Allowance.
- Hazardous and dangerous work allowance for occupations or jobs with hazardous or dangerous elements in the workplace.
- Attraction allowance, according to region and legal regulations.
- Allowances, subsidies, and living expenses are paid by Vietnamese agencies abroad.
- Emergency hardship allowance, work accident allowance, occupational disease allowance; one-time allowance for childbirth or adoption and other benefits as stipulated by social insurance law.
- Severance pay, unemployment benefits.
- Social welfare benefits and supplementary payments, which are not considered wages, are regulated by the government.
How to account for personal income tax for employees according to Circular 99.
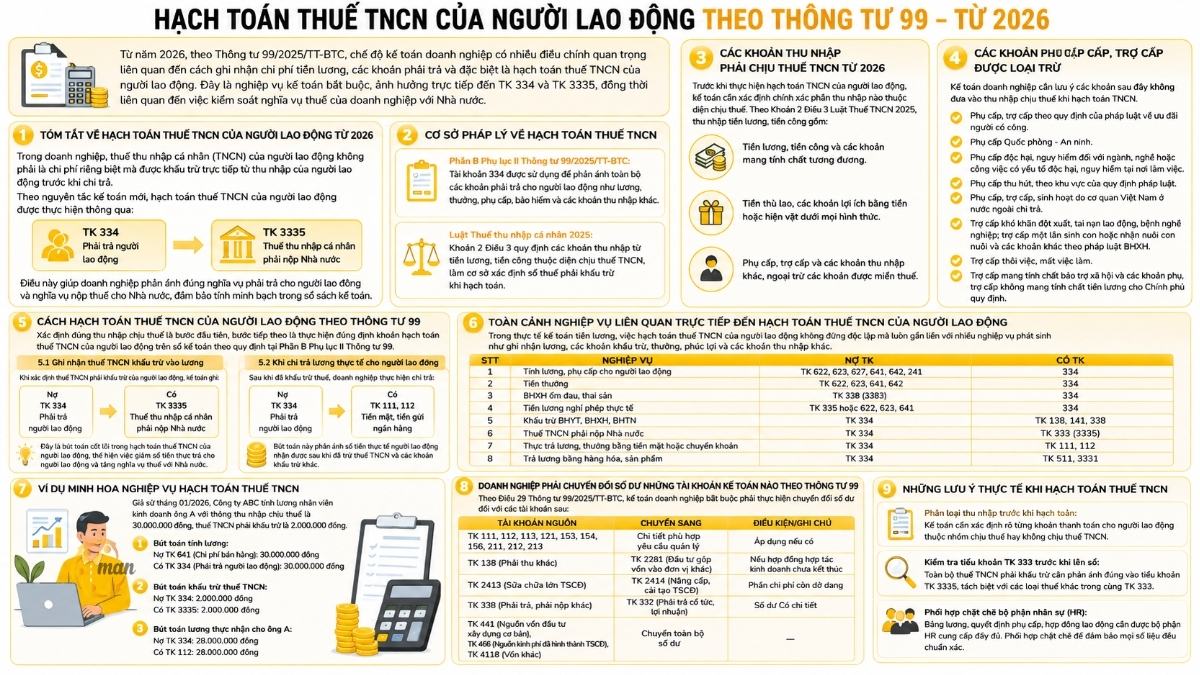
Determining the correct taxable income is the first step; the next step is to correctly record the personal income tax of the employee in the accounting books as prescribed in Part B, Appendix II of Circular 99.
Record the personal income tax deducted from salary.
When determining the personal income tax to be withheld from employees, the accountant records:
- Debit Account 334 – Payable to employees
- There is account 3335 – Personal income tax.
This is a core accounting entry in the personal income tax calculation for employees, reflecting a reduction in the actual amount paid to the employee and an increase in the tax liability to the State.
When paying actual wages to employees
After deducting taxes, the business makes the payment:
- Debit account 334
- There are accounts 111 and 112.
This accounting entry reflects the actual amount the employee receives after deducting personal income tax and other deductions.
An overview of the procedures directly related to the accounting of personal income tax for employees.
In payroll accounting practice, the accounting of personal income tax for employees is not independent but is always linked to many related transactions such as recording salaries, deductions, bonuses, benefits, and other income. To ensure that the taxable income and tax obligations are accurately reflected, accountants need to understand each specific journal entry below before determining and deducting personal income tax according to regulations.
| Operations | Debit Account | I have an account. |
| Calculate salaries and allowances for employees. | Account 622, 623, 627, 641, 642, 241 | 334 |
| Bonus | Accounts 622, 623, 641, 642 | 334 |
| Social insurance for sickness and maternity | TK 338 (3383) | 334 |
| Actual vacation pay | Account 335 or 622, 623, 641 | 334 |
| Deductions for health insurance, social insurance, and unemployment insurance. | Account 334 | Accounts 138, 141, 338 |
| Personal income tax payable to the State. | Account 334 | TK 333 (335) |
| Salaries and bonuses are paid in cash or via bank transfer. | Account 334 | Account 111, 112 |
| Paying wages with goods or products. | Account 334 | Account 511, 3331 |
Example illustrating the accounting process for personal income tax of employees.
Let's assume that in January 2026, ABC Company calculates the salary of sales employee Mr. A with taxable income of 30,000,000 VND and personal income tax to be withheld of 2,000,000 VND.
Payroll accounting entry:
- Debit Account 641 (Selling Expenses): 30,000,000 VND.
- Account 334 (Payable to employees): 30,000,000 VND.
Personal income tax deduction entry:
- Debit Account 334: 2,000,000 VND
- Account 333 has a balance of 2,000,000 VND.
Accounting entry for food received by Mr. A:
- Debit Account 334: 28,000,000 VND
- Account 112 has a balance of 28,000,000 VND.
Which accounting account balances must businesses convert according to Circular 99?
According to Article 29 of Circular 99/2025/TT-BTC, enterprise accountants are required to convert the balances of the following accounts:
| Source account | Switch to | Conditions/Notes |
| Account 111, 112, 113, 121, 153, 154, 156, 211, 212, 213 | Details that meet management requirements | Apply if applicable. |
| Account 138 (Other receivables) | Account 2281 (Investment in other entities) | If the business cooperation agreement has not yet ended |
| Account 2413 (Major repairs to fixed assets) | Account 2414 (Upgrading and renovating fixed assets) | The remaining outstanding costs |
| Account 338 (Other payables and liabilities) | Account 332 (Dividends and profits payable) | Credit balance details |
| Account 441 (Capital for basic construction investment)
Account 466 (Funding source for fixed assets) |
Account 4118 (Other Capital) | Transfer the entire balance. |
See more: Accounting chart of accounts according to Circular 99.
Practical considerations when accounting for personal income tax for employees.
Below are the points that accountants need to pay special attention to when accounting for personal income tax of employees during the period when Circular 99 is in effect:
- Income classification before accounting: Accountants need to clearly identify whether each payment account for employees falls under the category subject to personal income tax or not.
- Verify sub-account 333 before recording: All deductible personal income tax must be correctly recorded in sub-account 3335, separate from other taxes in the same account 333.
- Closely coordinate with the Human Resources (HR) department: Payroll, allowance decisions, and employment contracts must be fully provided by the HR department. Close coordination is essential to ensure all data is accurate.
Accountants need to clearly identify each payment to employees as belonging to the taxable or non-taxable group for personal income tax. Errors at this step directly affect the accounting data for employee personal income tax and the year-end tax return.
Businesses that do not have a dedicated accounting department may consider this option. full accounting service To ensure that income classification and personal income tax deductions are correct from the start.
Conclude
Properly accounting for employee personal income tax according to Circular 99/2025/TT-BTC helps businesses ensure accuracy in payroll management, tax obligations, and accounting records from 2026 onwards. In particular, accountants need to understand how to use Account 334 to reflect amounts payable to employees and Account 3335 to record personal income tax payable to the State.
Besides updating accounting methods, businesses also need to review all income, allowances, and subsidies to determine which are taxable or tax-exempt under the new regulations. Standardizing payroll accounting practices from the outset will help businesses minimize errors when filing taxes, settling taxes, and transitioning their accounting systems to the regulations applicable from 2026.
Contact MAN – Master Accountant Network For timely advice and support!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- E-mail: man@man.net.vn
- Google Business Profile: View MAN – Master Accountant Network's Google Business Profile
- LinkedIn Founder: View expert Le Hoang Tuyen's LinkedIn profile.
Responsible for production and professional content review by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant NetworkHe is a CPA Vietnam auditor with over 30 years of in-depth experience in accounting, auditing, taxation, and corporate legal consulting.
Frequently Asked Questions about Personal Income Tax Accounting for Employees
No. Personal income tax is a tax arising from the income of individual employees. Businesses only deduct, declare, and pay it on behalf of their employees. Therefore, when accounting for employees' personal income tax, accountants do not record this tax as an administrative expense, production expense, or selling expense.
Account 3335 is used when a business incurs personal income tax obligations to the State after deducting taxes from employees' income. The process typically includes: Determining taxable income, calculating the amount of personal income tax to be deducted, recording it through accounts 334 and 3335, and finally, paying the tax into the State budget.
Corporate accountants need to: Stay updated on new regulations regarding taxable income; Verify the list of income, allowances, and subsidies; Ensure consistency between payroll records, accounting ledger account 334, and tax obligations account 3335; and Review the conversion of the chart of accounts according to Circular 99/2025/TT-BTC. Can the personal income tax of employees be accounted for as a business expense?
When should account 3335 be used in accounting for employee personal income tax?
What should accountants keep in mind when accounting for employee personal income tax from 2026 onwards?






