
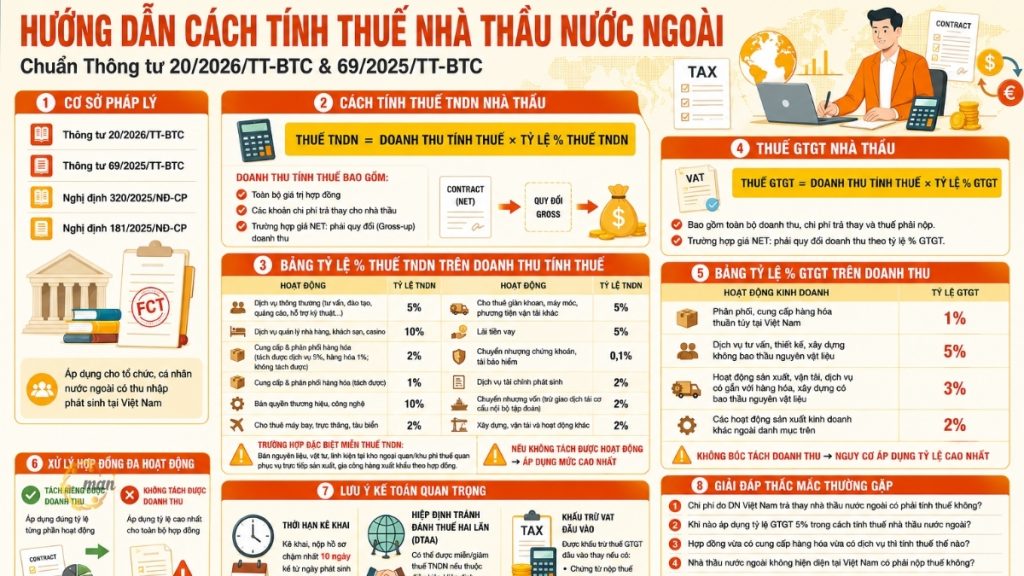
In the context of deep international economic integration, trade transactions between Vietnamese businesses and foreign partners are becoming increasingly common. For a professional tax accountant, mastering the methods of declaring and calculating Foreign Contractor Tax (FCT) is one of the mandatory requirements to optimize costs and prevent legal risks for businesses.
This article will provide a detailed and comprehensive analysis of the professional perspective on calculating foreign contractor tax using the revenue-based percentage method (direct method) in accordance with the core principles of... Circular 20/2026/TT-BTC, Circular 69/2025/TT-BTC along with related guiding decrees.
Legal basis and scope of application of the current method for calculating foreign contractor tax.
To accurately implement contractor tax accounting, corporate tax accountants first need to correctly identify the currently effective legal regulations. Currently, the legal framework directly governing this issue includes:
- Circular 20/2026/TT-BTC and Circular 69/2025/TT-BTC of the Ministry of Finance.
- Decree 320/2025/ND-CP provides detailed regulations on Corporate Income Tax (CIT).
- Decree 181/2025/ND-CP provides guidance on the implementation of the Value Added Tax (VAT) law.
The direct method of calculating foreign contractor tax applies to foreign organizations and individuals doing business in Vietnam or earning income in Vietnam who do not meet the conditions for paying tax under the deduction method (such as not having a permanent establishment in Vietnam, having a business period below the prescribed limit, or not implementing Vietnamese accounting regulations). This is the most common method, and Vietnamese businesses often have to declare and pay taxes on behalf of foreign contractors.
However, due to the complex nature of mixed tax systems, many businesses now choose to use them. tax accounting services To ensure accuracy and strict compliance with legal regulations.
How to calculate foreign contractor tax in relation to Corporate Income Tax.
Corporate income tax for contractors is a tax levied directly on the income generated within the territory of Vietnam by foreign legal entities. Determining this tax requires utmost care from accountants when breaking down revenue and applying tax rates.
General formula for calculating corporate income tax
According to the guidelines in Article 7 of Circular 20/2026/TT-BTC, the corporate income tax payable by the contractor is determined by the following formula:
|
Corporate income tax payable = Taxable revenue x Corporate income tax rate applied to taxable revenue |
Determining taxable revenue for corporate income tax purposes.
Taxable corporate income is the total value of cash flows actually received by the foreign contractor or foreign subcontractor from the Vietnamese side, before deducting any taxes payable.
- Overarching principle: Taxable revenue must include all expenses paid by the Vietnamese partner on behalf of the foreign contractor (if the contract stipulates that the Vietnamese party will bear these expenses such as airfare, accommodation, transportation, etc.).
- Technical handling when the contract specifies a NET price (excluding tax): When the signed contract records the net payment value to the contractor, the accountant is required to perform a gross-up of the revenue before applying the calculation formula.
The formula for converting net revenue to gross revenue for the purpose of calculating foreign contractor tax (corporate income tax) is as follows:
|
Taxable revenue (Gross) = Net revenue / 1 – % difference |
Table of corporate income tax percentages on taxable revenue
Below is a summary table of corporate income tax rates categorized by specific business sectors:
| Business lines | Corporate income tax rate % | Accounting practice notes |
| Standard service | 5% | Applicable to consulting, training, online advertising, technical support, etc. |
| Restaurant, hotel, and casino management services. | 10% | A particularly high tax rate applies to the accommodation and entertainment services sector, including gambling. |
| Supply and distribution of goods | If the charges can be separated: The service portion is subject to 5%, and the goods portion is subject to 1%.
If separation is not possible: Apply the general rate of 2% to the entire value. |
|
| Supply and distribution of goods | 1% | This applies to forms of import and export conducted locally or under Incoterms terms where the seller bears the risk within the territory of Vietnam. |
| Trademark and technology rights | 10% | Royalties, intellectual property transfer, software… |
| Aircraft, helicopter, and ship rental services. | 2% | This includes engine rental and accompanying spare parts. |
| Rental of drilling rigs, machinery, and other transportation vehicles. | 5% | Except for the aforementioned sea and air transport methods. |
| Interest on loans | 5% | Loans from foreign financial institutions or foreign parent companies. |
| Securities transfer, reinsurance | 0.1% | Based on the transfer value or reinsurance premiums sent overseas. |
| Financial services arising | 2% | International financial risk hedging tools. |
| Capital transfer | 2% | Based on the transfer price. Exclusion: Internal corporate restructuring transactions that do not alter the control of the ultimate parent company. |
| Construction, transportation and other activities | 2% | Applicable to construction projects with or without the inclusion of materials and international transportation services. |
Special cases exempt from corporate income tax: Foreign businesses selling raw materials, supplies, and components at bonded warehouses or free trade zones to directly serve their production and processing of export goods in Vietnam under export processing/manufacturing contracts will not be subject to corporate income tax. Accountants should note this point when establishing sales contracts to apply the most optimal method for calculating foreign contractor tax.
How to calculate Value Added Tax for foreign contractors
Alongside corporate income tax, value-added tax (VAT) for contractors is an indirect tax that the Vietnamese party is responsible for directly deducting at source before transferring money abroad to the contractor.
General formula for calculating VAT
Based on Article 13 of Decree 181/2025/ND-CP, the VAT value for contractors is calculated as follows:
|
VAT payable = Taxable VAT revenue x VAT rate (1% VAT rate) on revenue |
Contractor's VAT-taxable revenue
Specifically, accountants should note the following when determining the VAT-taxable revenue of contractors:
- Taxable revenue for VAT purposes is the total revenue received from providing services, or services associated with goods subject to VAT in Vietnam.
- This revenue includes all taxes payable and any expenses incurred by the Vietnamese side on behalf of the foreign contractor.
In the case of a Net Price contract: Similar to corporate income tax, if the committed cash flow is the net price, the accountant must convert the revenue for VAT calculation using the following formula:
|
Taxable VAT revenue = Contract value (Net price) / 1 – VAT rate calculated on revenue |
Table of VAT percentage rates on revenue
Each type of business activity of a foreign contractor will correspond to a separate VAT rate; corporate accountants should take note of the table below:
| Business activities of foreign contractors | The % ratio is used to calculate VAT. |
| Distribution and supply of goods within Vietnam. | 1% |
| Consulting, design, and construction services do not include the supply of materials. | 5% |
| Production, transportation, and service activities related to goods, and construction with material procurement included. | 3% |
| Other business activities not listed above. | 2% |
Note: Determining the correct VAT rate (%) for each activity group is crucial when calculating taxes for foreign contractors. If a contractor contract includes multiple business activities, accountants need to separate the revenue of each part of the work to apply the correct corresponding tax rate. If the value of each activity cannot be specifically separated, the tax authorities may apply the highest rate to the entire contract value, significantly increasing the tax liability and the risk of future tax arrears.
Principles for handling multi-operation contracts
In practice, a contract signed with a foreign contractor often does not simply contain a single activity, but may include many different items (both supplying machinery and equipment, providing installation services, technology transfer, and operational training).
For these complex contracts, the regulations on how to calculate foreign contractor tax clearly state:
- If the value of each activity can be separated: Accountants are allowed to break down the revenue of each part to apply the correct % ratio for calculating VAT corresponding to that activity.
- If the value of each activity cannot be separated: Businesses are required to apply the highest VAT rate (%) applicable to the business activities specified in the contract to the entire total value of the contract.
Advice for accountants: Proactively advise the board of directors and the purchasing department right from the contract drafting stage. Clearly separating the value of equipment (subject to VAT rate 1%) and technical services (subject to VAT rate 5%) in the contract appendix will help businesses save a huge amount of tax compared to having to combine them under the 5% rate for the entire contract.
To best manage risk in large transactions, the role of the head of the finance department is extremely important. Therefore, hire chief accountant Experienced professionals can help businesses thoroughly assess contract terms from the outset, thereby optimizing their tax obligations.
An illustrative example of how to calculate tax for foreign contractors.
To help corporate accountants better visualize the accounting and calculation process based on real-world data, let's analyze the following specific situation.
Hypothetical scenario
Company A (Vietnam) signs a technical consulting service contract with Company B (Japan).
- The contract value payable to the Japanese side (Net price) is: USD 100,000.
- According to the contract terms, Company A is responsible for paying all contractor taxes arising in Vietnam.
- Technical consulting activities fall under the category of services subject to VAT at a rate of 5% and corporate income tax at a rate of 5%.
- The assumed exchange rate on the payment date is: 25,000 VND/USD.
Calculation process
The calculation steps are as follows:
Step 1: Convert the contract value to Vietnamese Dong (VND)
|
Net revenue (VND) = 100,000 USD x 25,000 VND/USD = 2,500,000,000 VND |
Step 2: Apply the method for calculating foreign contractor tax to determine the taxable revenue for corporate income tax purposes.
Since this is a net contract, the accountant performs the gross-up of corporate income tax first:
|
Taxable revenue for corporate income tax = 2,500,000,000 / (1 – 5%) = 2,631,578,947 VND |
The amount of corporate income tax the contractor has to pay is:
|
Corporate income tax payable = 2,631,578,947 x 5% = 131,578,947 VND |
Step 3: Determine the revenue subject to VAT.
The revenue subject to VAT is determined based on revenue including corporate income tax but excluding VAT. Therefore, the revenue subject to VAT is equal to the revenue subject to corporate income tax calculated above, which is VND 2,631,578,947.
The VAT amount payable by the contractor is 131,578,947 VND.
Summary of tax obligations incurred by the contractor:
- Total tax payable by the contractor: 131,578,947 (Corporate Income Tax) + 131,578,947 (VAT) = 263,157,894 VND.
- Total actual payment value of the business in Vietnam: 2,500,000,000 (Net) + 263,157,894 (Tax paid on behalf of) = 2,763,157,894 VND.
The correct execution of the steps in How to calculate tax for foreign contractors The above requires meticulous attention to detail. If your internal accounting team is insufficient to handle the workload, your company may consider hiring someone else. hire accounting services Professionalism is key to handling declaration and settlement procedures quickly and accurately.
Key considerations for accountants when calculating foreign contractor tax.
To avoid administrative penalties or tax assessments due to professional errors, accountants need to pay special attention to the following key points during their work:
Deadline for declaring and paying contractor tax
Unlike regular taxes that are declared periodically on a monthly/quarterly basis, foreign contractor tax is declared each time a payment is made.
- Deadline for filing tax returns: No later than the 10th day from the date the tax liability arises (the date the Vietnamese enterprise transfers payment to the foreign contractor).
- If a business makes multiple payments to different contractors within a month, the accountant can register with the tax authority to switch to monthly filing to reduce administrative burden.
Double Taxation Avoidance Agreement (DTAA)
Some foreign contractors from countries that have signed Double Taxation Avoidance Agreements with Vietnam may be eligible for exemption or reduction of corporate income tax in Vietnam. However, this exemption or reduction does not occur automatically. Vietnamese corporate accountants must still complete the full procedure of notifying the tax authorities of the exemption or reduction under the Agreement within the prescribed timeframe. If this submission step is missed, the tax authorities will still collect the tax and impose penalties according to Vietnamese law.
Input VAT deduction for contractor tax paid on behalf of another party.
When paying VAT on behalf of a foreign contractor, this amount constitutes input VAT for the Vietnamese enterprise. The enterprise's accountant is fully entitled to declare and deduct the entire amount of VAT paid by this contractor if all the following conditions are met:
- There is proof of payment of foreign contractor tax (receipt for payment into the state budget in cash or by bank transfer).
- Non-cash payment documents for the value of services paid to foreign contractors under contract.
Reference: New points in Circular 20/2026/TT-BTC.
Frequently Asked Questions about Calculating Tax for Foreign Contractors
Yes. Expenses paid by the Vietnamese side on behalf of foreign contractors, such as airfare, hotel, accommodation, travel, or other support related to contract execution, must be added to taxable revenue for contractor purposes if they are the responsibility of the foreign contractor. Accountants need to carefully review the contract terms to avoid omitting taxable revenue when declaring it.
The VAT rate 5% is typically applied to service or construction activities that do not include the supply of materials. Common examples include consulting, design, training, technical support, marketing, or other professional services provided by foreign organizations to businesses in Vietnam.
For mixed contracts, accountants need to separate the value of goods and services to apply the correct VAT and corporate income tax rates to each component. If the revenue from each activity cannot be separated, the tax authorities may apply the highest rate to the entire contract value.
Yes. The fact that a foreign contractor does not have an office or commercial presence in Vietnam does not mean they are exempt from tax. As long as they generate income related to the supply of goods and services to an organization in Vietnam, they may still be subject to foreign contractor tax according to current regulations.
In practice, the Vietnamese party is often the entity responsible for deducting, declaring, and paying contractor tax on behalf of the foreign organization. Therefore, the accounting department needs to carefully check the payment timing, contract type, net or gross price terms, and related documentation to ensure correct declaration in accordance with regulations. Are costs paid by Vietnamese businesses on behalf of foreign contractors subject to tax?
When is the VAT rate 5% applied in calculating foreign contractor tax?
How is contractor tax calculated for a contract that includes both the supply of goods and services?
Do foreign contractors who are not present in Vietnam have to pay taxes?
Is it the Vietnamese company or the foreign contractor that is responsible for declaring and paying taxes?
Conclude
Understanding and flexibly applying the method of calculating foreign contractor tax is not only a legal compliance responsibility of the accounting department, but also a solution that helps businesses proactively control costs in international cooperation projects. Hopefully, through this article, the corporate tax accounting department has been fully equipped with the tools for calculation and the most accurate tax rate schedule according to Circular 20/2026/TT-BTC and related documents.
For any questions or further information, please contact your company. Contact MAN – Master Accountant Network For free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- Email: man@man.net.vn
Content production by: Mr. Le Hoang Tuyen – Founder & CEO of MAN – Master Accountant NetworkCPA Vietnam auditors with over 30 years of experience in accounting, auditing, and financial consulting.






