
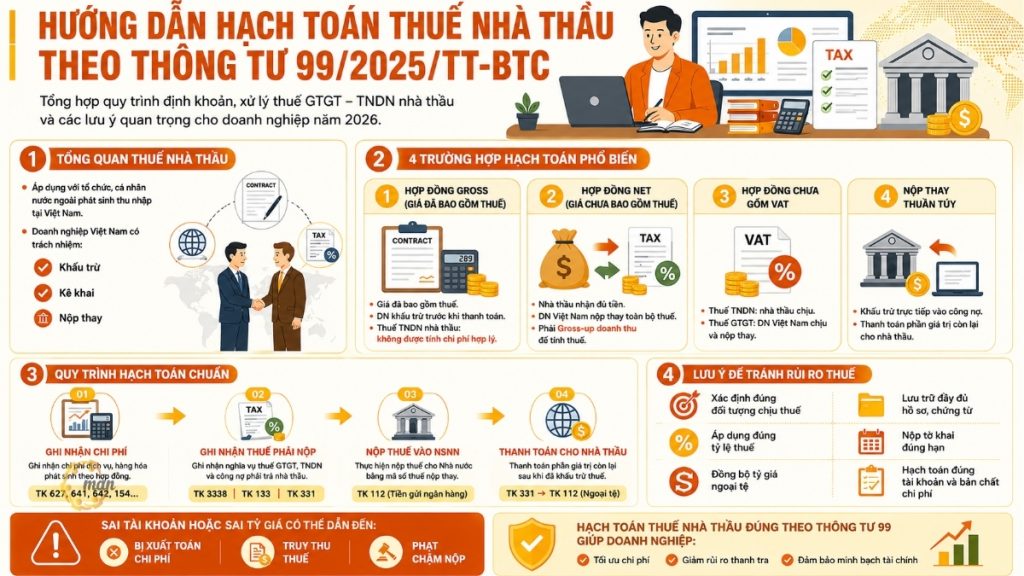
In the context of deep international economic integration, Vietnamese businesses are increasingly engaging in transactions involving the purchase and sale of goods and services with foreign partners. This entails the obligation to declare, deduct, and pay foreign contractor tax (FCT). To fulfill legal obligations and optimize business costs, a thorough understanding of contractor tax accounting procedures according to Circular 99 is crucial for every accountant.
This article will provide you with a comprehensive and in-depth guide to the contractor tax accounting process. Circular 99/2025/TT-BTC Applicable for fiscal year 2026, this helps businesses smoothly process data and be prepared for any tax audit.
The nature of business operations and the importance of accounting for contractor taxes according to Circular 99.
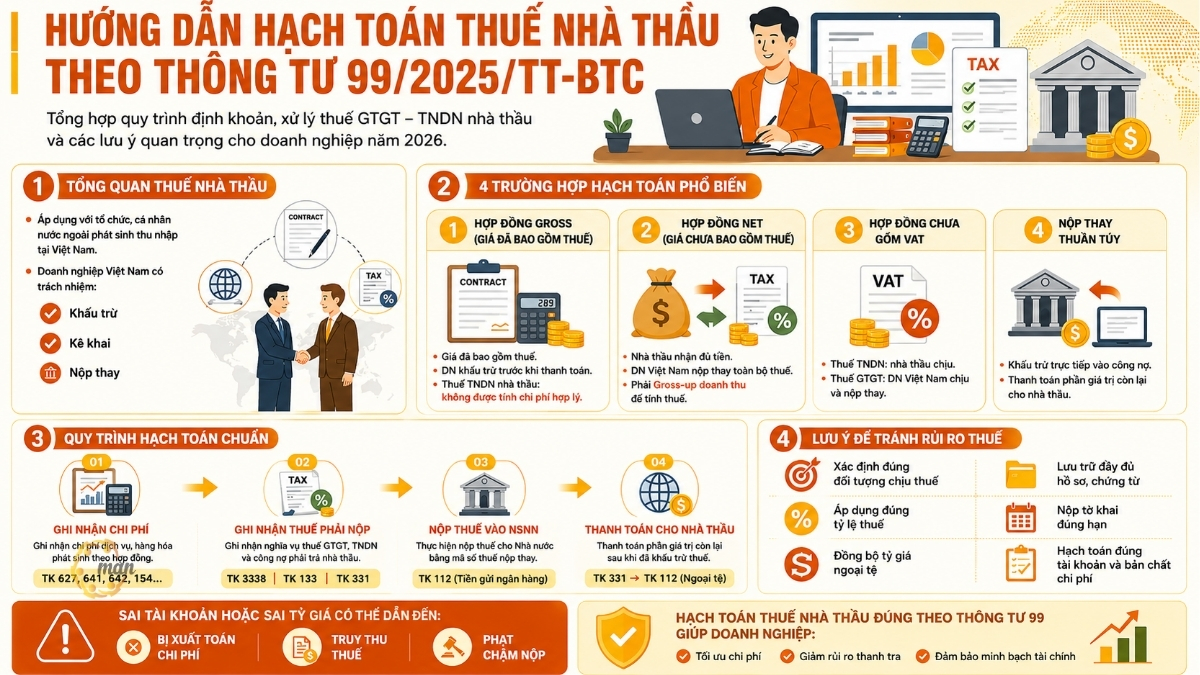
Foreign contractor tax is a tax applied to foreign organizations and individuals that do not operate under Vietnamese law but generate income from providing services or goods accompanied by services within Vietnam. When such transactions occur, the Vietnamese party is obligated to deduct, declare, and pay the tax on behalf of the foreign partner.
Understanding how to account for contractor tax according to Circular 99 is of particular interest to businesses from 2026 onwards due to changes and improvements in the legal framework for accounting and the management of tax registration for substitute payments. Circular 99 provides detailed guidance on the tax management process and the registration of a 10-digit tax code (subsidiary tax code) to facilitate budget payments. If accountants do not fully understand the principles of accounting for contractor tax according to Circular 99, businesses are very likely to fall into risks such as incorrect account entries, using incorrect foreign exchange rates, leading to the disallowance of expenses during corporate income tax settlement or penalties for late tax payments.
To assist in controlling the flow of substitute payments and systematizing digitized documents, businesses can refer to the following: online accounting services Professional services from reputable organizations are available to assist in reviewing and ensuring full compliance with tax obligations, thereby protecting the interests and image of the business.
Methods for accounting for contractor tax according to Circular 99 for each type of contract.
Depending on the terms of the tax liability agreement stipulated in the economic contract between the Vietnamese enterprise and the foreign contractor, the accountant will choose the appropriate accounting method. Below are four of the most common practical scenarios when accounting for contractor tax according to Circular 99.
Accounting for contractor tax according to Circular 99 for contracts with gross price (price including tax)
A gross price contract is a case where the agreed-upon value in the contract includes all VAT and corporate income tax for the contractor. Vietnamese businesses are responsible for deducting this tax amount directly from the payment before transferring money abroad to the contractor.
In this case, since the contractor's corporate income tax is borne by the foreign party (deducted from their revenue), the Vietnamese enterprise is merely paying it on their behalf. Therefore, this portion of the corporate income tax is not considered a deductible expense for the Vietnamese enterprise.
Detailed accounting entry procedures
To accurately reflect the withholding tax transaction in the accounting system, accountants record the journal entries in the following specific order:
Step 1: Record accounts payable and taxes due.
Upon receiving a service invoice or acceptance certificate from a foreign contractor, the accountant proceeds to record the expenses and tax obligations:
- Debit accounts 627, 642…: Reflects production and business costs (the corresponding service value).
- Debit Account 811: Reflects the amount of corporate income tax incurred by the contractor (this amount is excluded during corporate income tax settlement as it is not considered a deductible expense).
- Debit Account 133: Reflects deductible input VAT (when there is documentation of tax payment made on behalf of another party).
- Account 331 reflects the value of accounts payable to foreign contractors (after deducting the contractor's tax liability).
- Account 3338 reflects the detailed amount of taxes that contractors must pay to the state budget (including VAT and corporate income tax).
Step 2: When the business pays taxes to the State Budget.
Based on the bank's confirmed successful payment receipt, the accountant proceeds to reduce the contractor's tax liability by making the following specific journal entry:
- Debit Account 3338: Reduce the contractor's tax liability.
- Account 112: Bank deposits (payments made by bank deposit).
Accounting for contractor tax according to Circular 99 for Net Price contracts (Price excluding tax)
For net price contracts, both parties agree that the foreign contractor will receive the full amount stated in the contract (actual amount received). All VAT and corporate income tax obligations arising in Vietnam will be borne by the Vietnamese enterprise.
Since the tax obligation rests with the Vietnamese enterprise according to the legally binding contract, this portion of corporate income tax paid on behalf of the contractor is considered a deductible expense when calculating corporate income tax for the Vietnamese enterprise. To account for contractor tax according to Circular 99 in this case, the accountant must convert the revenue from net price to gross price (gross-up revenue) before calculating the tax payable.
Detailed accounting entry procedures
Below is a detailed sequence of accounting entries to help businesses accurately record actual service costs and tax obligations after gross-up revenue:
Step 1: Record the payable amount to the foreign contractor based on the contract value.
Upon receiving the completion acceptance certificate or service invoice from the foreign partner, the accountant proceeds to record the actual costs and liabilities as follows:
- Debit accounts 627, 642…: Record expenses at the net value stated in the contract.
- Account 331 reflects the value of liabilities payable to foreign partners.
Step 2: Account for the contractor's VAT and corporate income tax obligations after conversion.
After applying the conversion formula to calculate the VAT and corporate income tax that the contractor pays on their behalf, the accountant records:
- Debit Account 133: Amount of deductible VAT (calculated on converted revenue).
- Debit accounts 627, 642…: The amount of corporate income tax borne by the contractor (considered a deductible expense).
- Account 3338 reflects the total amount of tax payable by the contractor.
Step 3: When paying taxes into the State Budget
- Debit Account 3338: Fulfillment of contractor tax obligations.
- Accounts 111 and 112 represent the company's cash or bank deposits.
See more: Instructions on how to calculate tax for foreign contractors.
Accounting for contractor tax according to Circular 99 when the contract does not include VAT.
Contracts stipulating that the payment value includes corporate income tax but excludes value-added tax (VAT) are a common type of mixed contract. In this case, corporate income tax is the responsibility of the foreign contractor (the Vietnamese enterprise deducts it directly from the payment), while VAT is the responsibility of the Vietnamese enterprise. Therefore, accounting for contractor tax according to Circular 99 for this type of contract requires extremely careful cost separation by the accountant.
Detailed accounting entry procedures
When this type of hybrid contract arises, accountants allocate costs and record journal entries following these specific steps:
Step 1: Record accounts payable and related tax obligations.
The accountant records the accounts payable and related tax obligations, specifically:
- Debit accounts 627, 642…: Reflects service costs after deducting the contractor's VAT.
- Debit Account 811: Reflects the amount of corporate income tax paid by the contractor (the portion of corporate income tax borne by the contractor, which the business deducts and therefore is not considered a deductible expense for the Vietnamese party).
- Debit Account 133: Reflects the amount of VAT that the contractor is entitled to deduct in Vietnam.
- Account 331 reflects the value of accounts payable to contractors after deducting the contractor's VAT portion of the contract.
- Account 3338 reflects the amount of tax payable by the contractor (including VAT and corporate income tax).
Step 2: When making tax payments to the Treasury on behalf of another party.
When making tax payments to the Treasury on behalf of someone else, the accounting entry is:
- Debit Account 3338: Reduction of contractor tax liability.
- Accounts 111 and 112 represent the company's cash or bank deposits.
Accounting for contractor tax according to Circular 99 in the case of purely substitute payment.
When a Vietnamese business signs a contract with a foreign contractor and agrees to pay the contractor's tax on their behalf, this tax accounting process needs to be carried out accurately and transparently to comply with tax and accounting regulations. Unlike the cases above, this process clearly reflects the direct deduction of the tax from the payable amount before transferring the funds abroad.
Detailed accounting procedures for making payments on behalf of others.
The process of recording expenses and deducting tax obligations paid directly on behalf of foreign partners is carried out sequentially in the following four standard steps:
Step 1: Record initial contractor costs incurred.
Based on the completed service records and handover document, the accountant records the total service value before tax:
- Debit accounts 627, 641, 642… (Depending on the nature of the expense and the department using the service).
- Account 331: Payable to foreign suppliers (amount before tax).
Step 2: Record the amount of tax the contractor is liable to pay and deduct it from the outstanding debt.
Accurately determine the VAT and corporate income tax payable to be directly offset against the payment obligations of foreign partners:
- Debit Account 331: Accounts Payable to Suppliers (reduce accounts payable to foreign contractors by the exact amount of tax paid on their behalf).
- Account 3338 reflects the contractor's tax obligations to the State budget.
Step 3: Paying contractor tax on behalf of the foreign contractor into the state budget.
- Debit Account 3338: Completion of contractor tax payment.
- Accounts 111 and 112: Deduct cash or bank deposits to pay taxes.
Step 4: Pay the remaining contract value to the foreign contractor.
After deducting the contractor's tax payment, the accountant transfers the remaining balance to the partner.
- Debit Account 331: Reduce all accounts payable to foreign contractors.
- Accounts 111 and 112 include: Bank deposits (foreign currency or equivalent Vietnamese Dong).
Synchronize exchange rates when accounting for contractor tax according to Circular 99.
One of the most significant updates since fiscal year 2026 is the standardization and synchronization of exchange rates when accounting for transactions and filing tax returns. Synchronizing exchange rates when accounting for contractor tax according to Circular 99 helps minimize unnecessary discrepancies between the company's accounting records and the tax authorities' final settlement figures.
- Determining the actual exchange rate: When foreign currency transactions arise with foreign contractors, businesses need to apply the actual buying/selling exchange rate of the commercial bank where the business regularly conducts transactions on the payment date or the date the debt is recorded.
- For net price contracts: Taxable revenue and the amount of tax paid on behalf of the contractor must be converted to VND according to the correct transfer selling exchange rate of the commercial bank on the date of payment to the contractor for accurate gross-up conversion.
- For gross price contracts: The exchange rate used for calculation is the exchange rate at the time the tax withholding obligation arises (the date of payment to the foreign partner).
Synchronizing this exchange rate data according to the new guidelines is an important step that helps accountants consistently record contractor tax according to Circular 99, limiting the risk of exchange rate discrepancies arising during subsequent tax audits.
Key considerations when accounting for contractor tax according to Circular 99 to avoid tax risks.
Tax inspection and audit procedures are becoming increasingly stringent thanks to modern information technology systems. For businesses that do not have a dedicated department with extensive international experience, careful consideration of alternative solutions is crucial. hire an external accountant This is an optimal decision that helps to tightly control the documentation process, thereby absolutely minimizing unintended errors.
To ensure the security of your company's tax settlement records, when accounting for contractor tax according to Circular 99, accountants need to understand the following key points:
Identify the correct taxable subjects and applicable tax rates.
Not all services provided by foreign contractors are subject to the same tax rate. Accountants must carefully study the nature of the transaction outlined in the contract (such as the supply of machinery and equipment, management consulting services, software licenses, or international transportation services, etc.) to apply the correct % rate for calculating VAT and corporate income tax as stipulated. Circular 103/2014/TT-BTCAccurately classifying foreign contractors and transaction types right from the initial stage is a core foundation for ensuring a smooth and accurate contractor tax accounting process under Circular 99.
Maintain complete and valid records and documents.
The documentation system is the only evidence that helps protect the legitimacy of expenses when tax authorities conduct on-site audits at businesses. When accounting for contractor tax according to Circular 99, businesses need to prepare and store a complete set of documents including:
- Service contract signed between the Vietnamese party and the foreign contractor (with detailed appendices if any).
- Foreign Contractor Tax Declaration Form (Form No. 01/NTNN).
- Receipt for payment into the state budget (document proving payment of contractor tax on behalf of a foreign contractor).
- Commercial invoice or payment request document provided by the foreign party.
- The service completion acceptance report bears the signatures of representatives from both parties.
- Non-cash payment vouchers.
Strictly adhere to deadlines for filing tax returns and paying taxes.
The deadline for filing tax returns and paying contractor tax is typically no later than the 10th day from the date the tax liability arises (which is the day the Vietnamese enterprise transfers payment to the foreign contractor) for cases where tax is filed on a transaction-by-transaction basis. If the enterprise registers to file contractor tax returns monthly, the deadline is no later than the 20th of the following month. Late filing of tax returns or payment of taxes on behalf of the contractor will result in administrative penalties and late payment interest charges as stipulated by the Tax Administration Law, leading to unexpected increased costs for the enterprise.
Ensure accurate accounting of accounts and the nature of expenses.
As analyzed in the previous sections, correctly accounting for expenses reflecting their nature is extremely important. For deductible VAT, accountants must accurately record it in account 133. For corporate income tax paid on behalf of others, accountants must clearly classify it: if the contract is at a gross price, it should be recorded in account 811 (non-deductible expense); if the contract is at a net price, it should be recorded in the corresponding departmental expense account such as 627 or 642 to be considered a reasonable expense when settling corporate income tax. This avoids confusion that could distort business results and lead to the risk of tax arrears.
Frequently Asked Questions regarding Contractor Tax Accounting under Circular 99
In practice, handling invoices, exchange rates, and documents from foreign contractors often gives rise to many complex situations. MAN – Master Accountant Network has compiled a list of questions and difficulties encountered when accounting for contractor taxes:
Yes. According to the accounting principles of Circular 99 and the corporate income tax law, if the economic contract clearly stipulates that the payment to the foreign contractor is the price excluding tax (Net price) and the tax payment obligation in Vietnam belongs to the Vietnamese party, then this corporate income tax paid on behalf of the contractor is deductible. The accountant needs to perform a gross-up to calculate the correct amount of tax payable, then record this corporate income tax expense in the corresponding departmental expense accounts (Accounts 627, 642, etc.) instead of in Account 811.
From January 1st, 2026, Circular 99/2025/TT-BTC will rename Account 112 from Bank Deposits to Demand Deposits. This change aims to accurately reflect the liquidity nature of deposit accounts at commercial banks. However, the accounting structure of this account when paying contractor taxes or making payments to foreign partners remains unchanged: Credit Account 112 when cash flows out to fulfill payment obligations or pay taxes to the state budget.
When paying taxes on behalf of foreign partners, Vietnamese businesses are required to register and use a separate 10-digit tax identification number for the substitute tax payment. Under no circumstances should contractor tax be paid under the same tax identification number used for the main business operations. In terms of accounting, the entire amount of substitute tax payments is recorded in the company's accounting system through the corresponding account TK 3338 (detailed for each contractor and each corresponding substitute tax identification number).
Circular 99/2025/TT-BTC significantly decentralizes decision-making authority and does not mandate the preparation of separate financial statements for dependent branches. Therefore, if a branch has direct transactions with foreign contractors, it can still record accounts payable (Account 331) and tax obligations paid on behalf of others (Account 3338) using its internal accounting software. At the end of the period, all this data will be synchronized and automatically transmitted to the head office for consolidation and centralized tax declaration and payment (or payment at the local location where the branch is headquartered, depending on the enterprise's tax management decentralization method). Is the corporate income tax paid by the contractor on behalf of the contractor under a net price contract considered a deductible expense when settling corporate income tax?
How does the change in the name of Account 112 in Circular 99/2025/TT-BTC affect the accounting of contractor tax?
If a business uses a tax identification number (10 digits) for tax payment on behalf of another party, how is the declaration and accounting of tax revenue managed?
According to Circular 99, if a branch does not prepare separate financial statements, how should contractor tax be accounted for?
Conclusion on the method of accounting for contractor tax according to Circular 99
Accounting for international transactions has never been a simple task for accountants due to its close relationship with foreign exchange rates, international tax policies, and domestic tax regulations. However, once the core principles and accounting methods for each specific type of contract are mastered, accounting for contractor tax according to Circular 99 will become much easier and more accurate.
For complex international problems, choosing consultants from specialized services or solutions is crucial. hire chief accountant Experienced professionals will be the optimal solution, ensuring maximum accuracy and consistency when comparing data with tax authorities.
Standardizing the contractor tax accounting process according to Circular 99 helps businesses establish a transparent accounting system, comply with current laws, and minimize risks arising during the 2026 tax settlement period. Always proactively control documentation, correctly identify the nature of contracts, and accurately apply accounting entries to optimize legitimate benefits for the business.
Contact MAN – Master Accountant Network For free support and advice!
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- Email: man@man.net.vn
Content production by: Mr. Le Hoang Tuyen – Founder and CEO of MAN – Master Accountant NetworkCPA Vietnam auditors with over 30 years of experience in accounting, auditing, and financial consulting.






