
Preparing the personal income tax withholding declaration is a mandatory obligation for organizations and individuals paying income. Entering 2026, with significant changes to the family allowance deduction and the progressive tax rate schedule, accountants need to master the process to avoid legal errors. This article will guide you step-by-step on how to accurately prepare the personal income tax withholding declaration (Form 05/KK-TNCN).
Why is it important to file the personal income tax withholding return on time?
Filing a personal income tax withholding declaration is not only about complying with the law but also helps businesses transparently disclose payroll expenses and protect the rights of employees. According to regulations... Circular 80/2021/TT-BTCEven if no tax deductions arise during the period, the paying organization must still file a tax return (except in certain special cases).
New update 2026: From January 1st, 2026, the personal allowance has increased to VND 15.5 million/month and the allowance for dependents to VND 6.2 million/month. This directly affects the figures when you file your personal income tax return.
Which individuals are required to file a personal income tax withholding declaration?
Details of the individuals required to file a personal income tax withholding declaration:
- Organizations and individuals paying income: All businesses and organizations paying income, including subsidiaries, branches, and business locations in provinces other than the head office, if they deduct tax, must prepare form 05/KK-TNCN (monthly/quarterly).
- Businesses deduct provisional tax: Payments for income not covered by employment contracts or employment contracts of less than 3 months.
- For businesses with branches in different provinces: If the head office pays salaries on behalf of the branch/subsidiary unit in another province, the head office is responsible for deducting and declaring the salary.
- Organizations pay income from other sources: capital investment, securities transfer, royalties, franchise fees, lottery winnings, etc.
Form No. 05/KK-TNCN Personal Income Tax Declaration
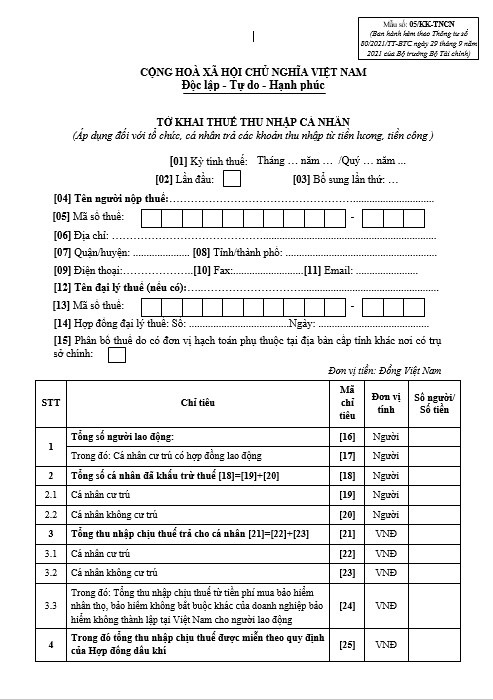
The personal income tax return form 05/KK-TNCN is stipulated in Circular 80/2021/TT-BTC and is used by organizations and individuals who pay income from salaries and wages. This form is prepared monthly or quarterly, depending on your declaration method, and applies in all cases, including when personal income tax withholding occurs and when no withholding occurs during the period.
Instructions for completing the Personal Income Tax Withholding Declaration Form (Form 05/KK-TNCN)
To assist in accurately and conveniently preparing the personal income tax withholding declaration, the following is a detailed guide on how to fill out Form No. 05/KK-TNCN. This content applies to organizations, businesses, or individuals responsible for paying income from salaries and wages and fulfilling their tax declaration obligations as prescribed.
You can refer to this to ensure that the declaration is completed and submitted correctly, in the proper format, and to minimize errors during the process.
General Information
In this section, taxpayers need to fully declare basic information related to the tax period and the income-paying entity. This is a crucial part that helps the tax authorities correctly identify the declarant, the time when the tax obligation arises, and the status of the file (initial declaration or supplementary declaration). When filling it out, it is necessary to accurately compare it with legal documents and information registered with the tax authorities to avoid errors. Specifically, as follows:
- [01] Tax period: Clearly state the filing period (monthly, annually, or quarterly/annually) corresponding to the tax liability period. If filing monthly, cross out the "quarterly" option; conversely, if filing quarterly, cross out the "monthly" option to avoid confusion.
- [02] First time: Check the box with an "X" if this is the first time you are filing for that tax period.
- [03] Supplement number: If it is not the first time filing, clearly state the sequential number of the supplementary filing (e.g., 1st time, 2nd time, etc.) according to the actual adjustments.
- [04] Taxpayer's name: Fill in the full name of the organization or individual paying the income exactly as it appears on the Business Registration Certificate, Establishment Decision, or Tax Registration Certificate.
- [05] Tax identification number: Record the correct tax identification number of the organization or individual paying the income as stated in the Tax Registration Certificate, Tax Identification Number Notification, or Tax Identification Number Card issued by the tax authority.
- [06], [07], [08] Address: Provide the registered office address for organizations; for individuals, provide the permanent address as stated on their ID card/citizen identification card registered with the tax authorities. The information must match all legal documents.
- [09], [10], [11] Telephone, fax, email: Provide complete contact information for the organization or individual paying the income so that the tax authorities can easily communicate with them when necessary. If there is no fax or email address, this field can be left blank.
- [12] Name of tax agent (if any): If you authorize a tax agent to file the tax return, clearly state the agent's name as it appears on the Business Registration Certificate or Establishment Decision.
- [13] Tax identification number: Enter the tax identification number of the tax agent as shown on the Tax Registration Certificate or Tax Identification Number Notification issued by the tax authority.
- [14] Tax agency contract: Record the contract number and date of signing between the organization/individual paying the income and the tax agent. Note that the contract must still be valid at the time of declaration.
- [15] Allocation of tax due to having a subsidiary accounting unit located in a different province from the head office: Mark "X" in the corresponding box if there is a need to allocate tax obligations to subsidiary units in other provinces/cities.
Section for listing indicators in the table
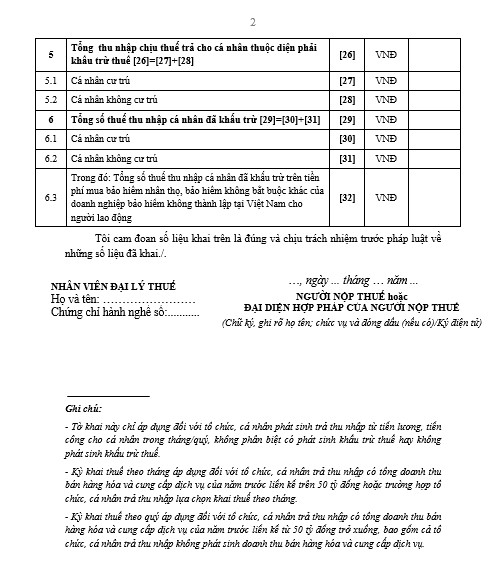
In this section, the income-paying entity needs to compile complete data on employees, taxable income, and the amount of tax withheld during the reporting period. The indicators are designed for each group (resident and non-resident individuals) to ensure accurate and transparent determination of personal income tax obligations. Specifically, as follows:
- [16] Total number of employees: This refers to the total number of individuals who received income from organizations or individuals during the tax period, regardless of whether tax deductions were made or not.
- [17] Individuals residing in Vietnam who have an employment contract: Record the total number of resident individuals who have signed employment contracts for 3 months or more and whose income is paid by the employer during the reporting period.
- [18] Total number of individuals whose taxes were deducted: Determined by the sum of indicators [19] and [20].
- [19] Individuals residing in Vietnam: This refers to the number of resident individuals whose income from salaries and wages has been subject to tax withholding by the organization or individual paying the income during the period.
- [20] Non-resident individuals: This refers to the number of non-resident individuals whose income from salaries and wages has been subject to tax withholding during the tax filing period.
- [21] Total taxable income paid to individuals: By the sum of indicators [22] and [23].
- [22] Individuals residing in Vietnam: This is the total taxable income arising from salaries, wages, and similar payments made by the entity to resident individuals during the period.
- [23] Non-resident individuals: This is the total taxable income from salaries, wages, and wage equivalents paid to non-resident individuals during the reporting period.
- [24] Total taxable income from premiums for life insurance and other non-mandatory insurance purchased by insurance companies not established in Vietnam for employees: This is the total value of life insurance premiums and other non-mandatory insurance policies with accumulated savings provided by foreign insurance companies (not established in Vietnam), which the entity has purchased for its employees and which are subject to tax.
- [25] Total taxable income exempted under the provisions of the Oil and Gas Contract: This refers to the portion of taxable income that is exempt (if any) according to specific provisions in the oil and gas contract.
- [26] Total taxable income paid to individuals subject to tax withholding: Determined by indicator [27] + [28].
- [27] Individuals residing in Vietnam: This is the total taxable income paid to resident individuals subject to tax withholding as stipulated by regulations during the period.
- [28] Non-resident individuals: This is the total taxable income paid to non-resident individuals subject to tax withholding during the reporting period.
- [29] Total amount of personal income tax withheld: By the sum of indicators [30] and [31]
- [30] Individuals residing in Vietnam: This is the amount of personal income tax that organizations and individuals paying income have withheld from resident individuals during the period.
- [31] Non-resident individuals: This is the amount of personal income tax withheld from income paid to non-resident individuals during the period.
- [32] Total amount of personal income tax withheld on premiums for life insurance and other non-mandatory insurance purchased by insurance companies not established in Vietnam for employees: This is the total amount of personal income tax withheld from life insurance premiums and other non-mandatory insurance policies with accumulated savings provided by foreign insurance companies to employees.
Indicator [32] is determined by the formula:
|
[32] = [24] x 10% |
Note: For individuals who have had personal income tax deducted for at least one month, indicators 26, 27, and 28 are calculated as follows:
- Criterion [27] Resident individuals: Total taxable income (TNCT) of labor with ≥1 tax line withholding >0, and:
| Type of contract | Condition |
| Employment contracts of 3 months or more | Individuals residing in Vietnam |
| Employment contracts of less than 3 months or not registered. | Individuals residing in Vietnam |
- Criterion [28] Non-resident individuals: Total taxable income of labor with ≥1 tax line withholding >0, contract type: non-resident.
- Indicator [26] Total taxable income paid to individuals subject to tax withholding equals the sum of 2 indicators [27] and [28]
Deadline for filing personal income tax returns and paying personal income tax.
Specifically, the deadlines for submitting personal income tax returns and paying taxes are as follows:
Deadline for submitting personal income tax deduction declarations.
Based on Article 44 of the Law on Tax Administration No. 38/2019/QH14 issued on June 13, 2019, the deadline for submitting tax returns is as follows:
- Monthly tax filing: The deadline is no later than the 20th day of the month following the month in which the tax liability arises (for example, the deadline for filing the tax return for February 2026 is no later than March 20, 2026).
- Quarterly tax filing: The deadline for filing and paying taxes quarterly is the last day of the first month of the quarter following the quarter in which the tax liability arises. (If the filing date falls on a public holiday, the filing will be done on the next working day after the holiday.)
Deadline for paying personal income tax
The deadline for paying personal income tax is no later than the last day of the tax return filing deadline.
For cases of supplementary tax filing, the deadline for tax payment is the same as the deadline for filing the tax return for the tax period containing the error. (According to Clause 1, Article 55, Law on Tax Administration 38/2019/QH14).
Note:
- When errors are discovered and a supplementary personal income tax return needs to be filed, the organization or individual must prepare an additional supplementary return using form 05/KK-TNCN for each month or quarter in which the error occurred.
- Only organizations or individuals that make income payments from salaries and wages are required to file personal income tax returns. If no such payments are made, no tax return needs to be submitted for that month/quarter (according to Decree 126/2020/ND-CP and Official Letter 2393/TCT-DNNCN).
Conclude
Understanding and accurately declaring each item on the personal income tax return not only helps businesses comply with legal regulations but also minimizes the risk of errors, tax arrears, and penalties later on. In particular, items related to taxable income and the amount of tax withheld need to be carefully reviewed to ensure that the figures match correctly between the tax return and the actual supporting documents.
If you lack confidence in compiling, verifying, and settling personal income tax, choosing a professional firm to assist you will save time and significantly reduce risks. Check it out now! Tax settlement services To receive comprehensive, compliant, and cost-effective support for your business.
Contact information MAN – Master Accountant Network
- Address: No. 19A, Street 43, Tan Thuan Ward, Ho Chi Minh City
- Mobile/Zalo: 0903 963 163 – 0903 428 622
- Email: man@man.net.vn
Content production by: Mr. Le Hoang Tuyen – Founder & CEO MAN – Master Accountant Network, Vietnamese CPA Auditor with over 30 years of experience in Accounting, Auditing and Financial Consulting.
Frequently Asked Questions about Preparing the Personal Income Tax Withholding Declaration
According to current regulations applicable in 2026, if salaries are paid during the period, a personal income tax withholding declaration must still be prepared to report the total income paid, except in cases where the enterprise is exempt from declaration under specific provisions of the Tax Administration Law.
The penalty can range from 2 million to 25 million VND depending on the length of the late filing period. Therefore, proactively filing your personal income tax withholding return on time is extremely important. If there are no personal income tax deductions, do I still need to file a tax return?
What is the penalty for late filing of tax returns in 2026?






